Fast Business Funding in Columbus, Ohio: State Capital, Buckeye Talent & Main Street Capital (2026)
Columbus is Ohio's largest city — state government, Ohio State, insurance and banking headquarters, and the Intel-driven tech corridor, plus neighborhood Main Streets from the Short North to German Village. What fast funding looks like in Columbus, which product fits which need, and how to compare offers.
Need funding fast? Apply in about 2 minutes — get a decision within hours, with no hard credit pull for pre-approval.
Apply Now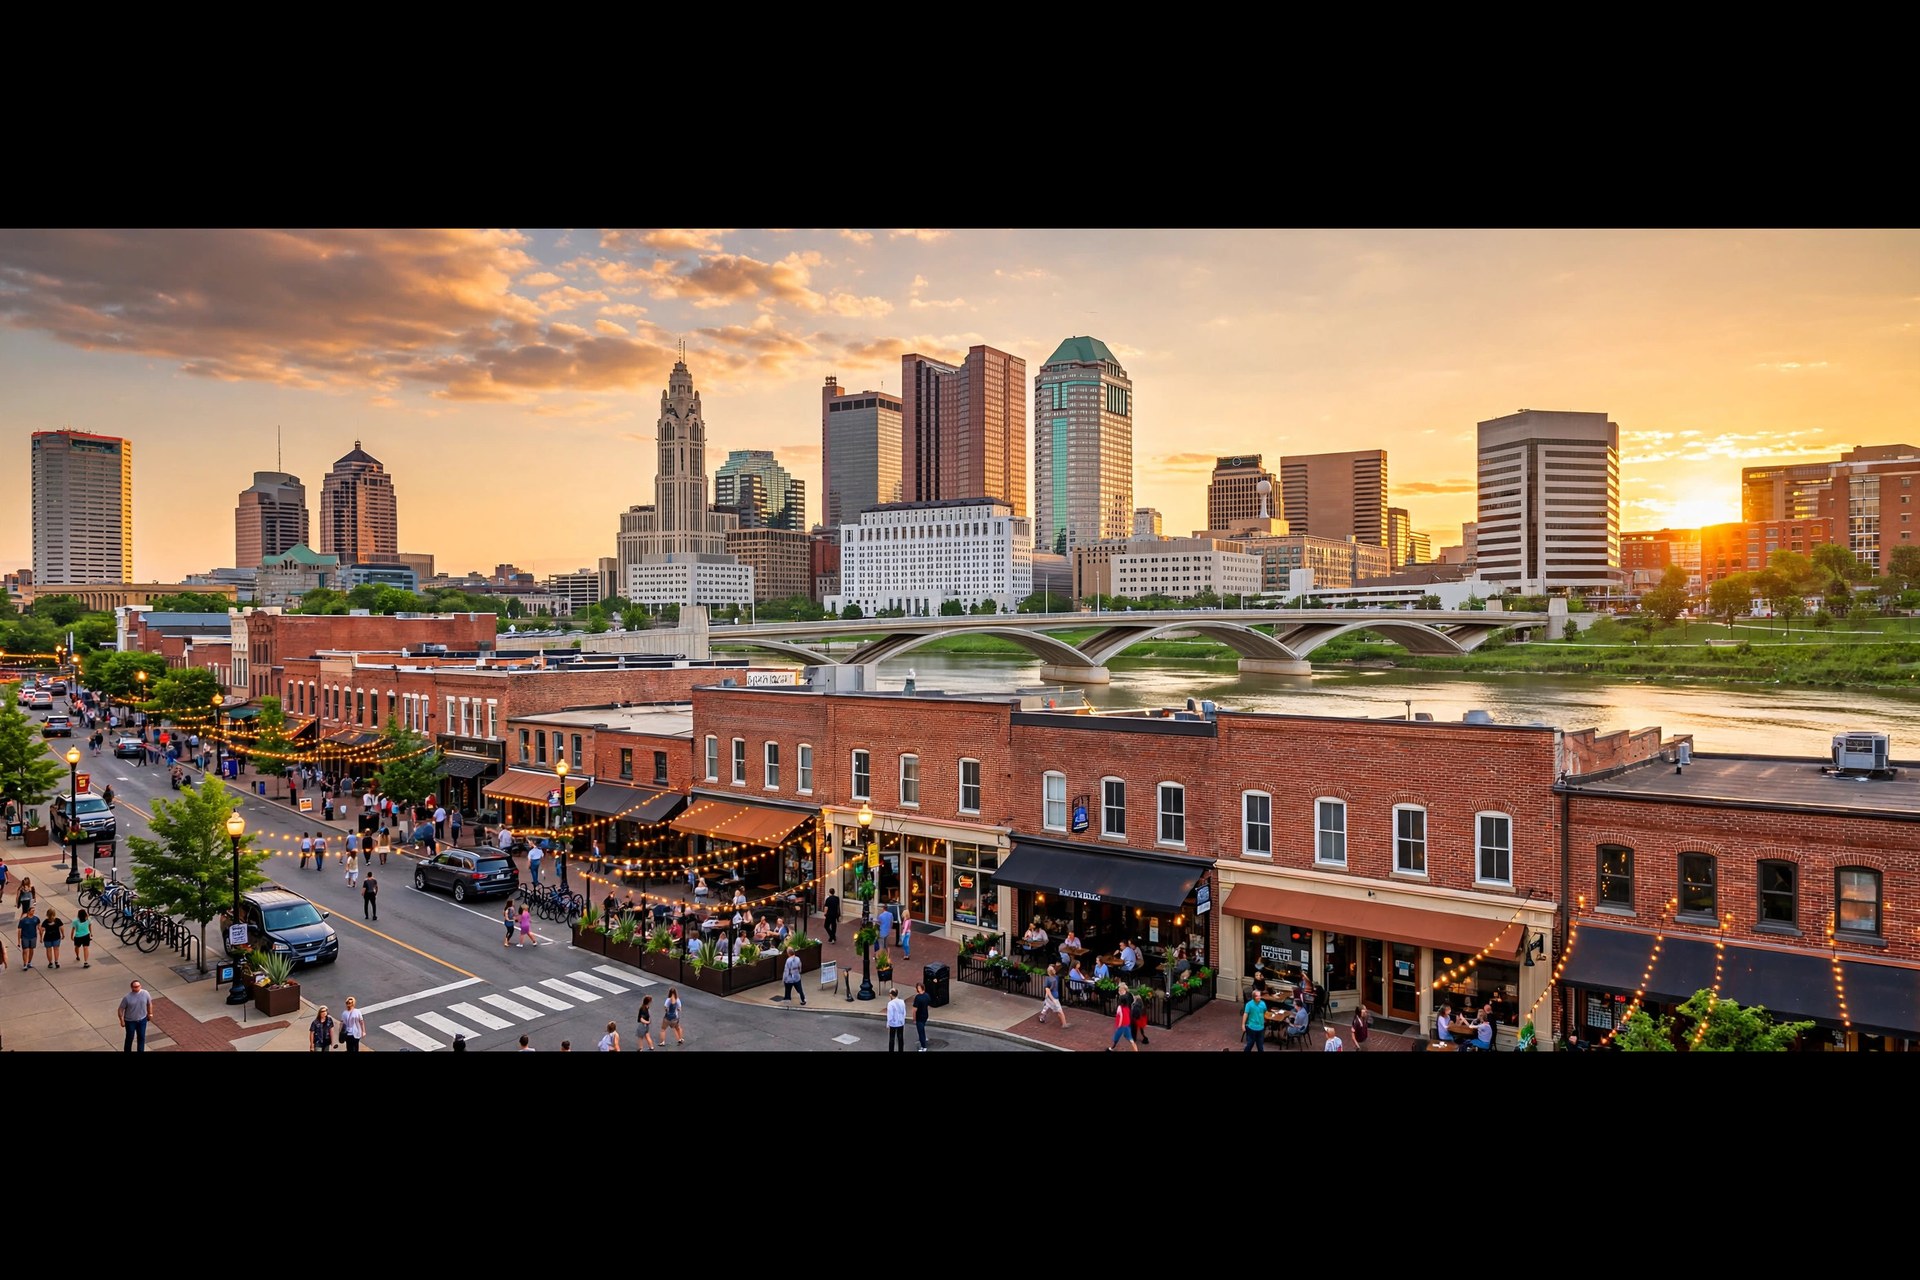
Key Takeaways
- Columbus is Ohio's largest city (about 938,000 residents in the July 2025 Census estimate, roughly 2.2 million across the metro area) and the state capital.
- Alternative lenders decide in hours and fund in 24–72 hours for Columbus businesses; banks typically take 30–90 days for the same money.
- The funding engines here are distinct: state government and Ohio State University; insurance and banking headquarters; the Intel semiconductor corridor in New Albany and the data-center build-out; and the neighborhood retail and restaurant strips of the Short North, German Village, and the Arena District.
- Columbus added jobs at roughly 10 times the national rate in the year to December 2025 — the fourth-fastest rate among the nation's 55 largest metro areas — which means growing businesses here borrow for hiring and capacity, not just survival.
Columbus is easy to misread as a government town. It is really several economies sharing one fast-growing metro: the statehouse and the agencies around it, one of the country's largest universities, the headquarters of Nationwide and Huntington, the JPMorgan Chase operations hub, the semiconductor and data-center corridor rising northeast of the city, and the neighborhood Main Streets that serve the people all of it employs. Each one borrows for a different reason, on a different timeline — and each one gets a different answer from a bank.
A restaurant in the Short North needs to staff up before a home football weekend, not after it. A supplier to a state agency needs to float payroll while a government invoice pays on its own schedule. A contractor needs materials for a job that pays on completion. Traditional banks move slowly for all three — and often decline the smallest files outright. Alternative lenders underwrite on bank deposits, not paperwork volume, and fund in days.
What's in this guide
Why Columbus Businesses Need Fast Capital
Columbus's economy runs on several engines, and each one creates a different cash crunch.
Government and the university. The State of Ohio, Ohio State University, and the federal government account for an estimated 55,000 to 60,000 jobs in Central Ohio, and adding Columbus City Schools, the City of Columbus, and Franklin County pushes the public-sector total to about 80,000. Around them sits an ecosystem of contractors, suppliers, staffing firms, and professional services. That work is steady, but it pays on institutional timelines — and a supplier that lands a state contract often has to hire and stock up weeks before the first payment lands.
Insurance, banking, and headquarters. JPMorgan Chase is Central Ohio's largest financial-sector employer, Nationwide Insurance is headquartered in Columbus, and Huntington Bank is headquartered here too. Add the headquarters and back-office operations of retailers, logistics firms, and health-care companies, and you get a deep white-collar daytime economy — the lunch crowds, dry cleaners, gyms, and retailers of downtown, the Arena District, and Easton borrow to catch that traffic, not after it arrives.
The tech and manufacturing corridor. Intel's planned semiconductor mega-site in New Albany, Anduril's drone manufacturing plant in northern Pickaway County, and data centers across the region have made Central Ohio a national tech and manufacturing story. Federal jobs data showed the Columbus region adding 20,607 jobs in the year to December 2025, a 1.9 percent increase — the fourth-fastest rate among the nation's 55 largest metro areas and roughly 10 times the national jobs growth average. Startups and their suppliers borrow for hiring, equipment, and the gap between a signed contract and first revenue — the classic timing problem of a fast-growing economy.
Neighborhood Main Streets. The Short North's High Street, German Village's brick streets, the Arena District, Clintonville, Grandview, Dublin, and Easton support independent retailers, restaurants, salons, and service businesses across a city that keeps adding residents — about 7,700 more in the year to July 2025 alone, the largest gain of any Ohio city. These firms borrow smaller amounts for build-outs, inventory, and seasonal staffing — exactly the file sizes banks are least interested in.
Best Funding Options in Columbus
The headline numbers above describe the revenue-based market in general, not any single offer: actual terms depend on your deposits, time in business, and industry. What matters for a Columbus file is matching the product to the timing of the need.
Revenue-based funding (merchant cash advance). The workhorse for speed. Approval is driven by recent bank deposits, not by a perfect credit file, and funding lands in days. It fits seasonal staffing, inventory before a surge, and short-term gaps — and it is expensive relative to a bank loan, so it should be sized to a need that pays for itself quickly.
Business term loans. A fixed monthly payment over a set term, better for a defined purchase — a kitchen build-out, a delivery truck, a second location's first-year rent — where the cost is known and the payback period is measured in years, not weeks.
Business lines of credit. Revolving access you draw only when needed. The best fit for the government supplier waiting on an agency payment, or the retailer smoothing the gap between inventory purchase and holiday-season sales.
Equipment financing. The equipment secures the loan, so underwriting is often easier than for unsecured working capital. A Short North restaurant's ovens, a New Albany supplier's machinery, or a distributor's box truck all fit here.
SBA loans. The cheapest money, and the slowest: 30–90 days is normal, and the paperwork bar is real. SBA fits the big, planned purchase — buying a building, a major expansion — not the payroll gap this Friday.
Which Product Fits Which Need
| Your need | Best first product | Why |
|---|---|---|
| Staff up before a home football weekend or convention | Revenue-based funding | Funds in days, sized to the event |
| Float payroll while a state agency or university pays on terms | Line of credit | Draw only what the gap requires, repay when the invoice clears |
| Kitchen build-out or restaurant equipment | Equipment financing or term loan | The asset secures it; payments match its useful life |
| Buy a second location or a building | SBA loan | Lowest cost for a long-lived asset — start early |
| Inventory before the holiday or back-to-school season | Revenue-based funding or line of credit | Speed matters more than the last point of cost |
| Fleet repair or a delivery vehicle | Equipment financing | Vehicle as collateral, fast underwriting |
What Funders Actually Weigh on a Columbus File
Revenue-based funders start with your bank statements, not your business plan. Three things move the offer most:
Deposit consistency. Funders look for steady monthly deposits over the last 3–6 months. A Short North restaurant with a strong football weekend and a soft January still qualifies — but the offer is sized to the average, not the peak, and a sharp recent drop will shrink it.
Existing obligations. A business already carrying daily-debit payments gets a smaller offer, or a decline, because the funder is underwriting what is left after current payments. Paying down an existing advance before applying is the single most effective way to raise the next offer.
Industry and seasonality. Funders know Columbus's seasonal patterns — the university calendar, home football weekends, convention traffic downtown, and the holiday surge at Easton and Dublin — and they price for them. A file that explains its seasonality up front (last year's monthly deposits, the upcoming bookings) reads as lower risk than one that leaves the funder to guess.
Credit score matters less than most owners expect on revenue-based files: scores in the 500s routinely get funded, with the score affecting cost more than the yes-or-no. Bank and SBA files are stricter — typically 650-plus — and they also weigh time in business, collateral, and tax returns more heavily.
The Documents: Short List, No Surprises
For a revenue-based application, the standard ask is short:
- Last 3–6 months of business bank statements
- A completed application (owner, business, and revenue details)
- Government-issued ID and a voided check are sometimes requested for verification on specific products before funding — but neither is a universal upfront requirement to see your offers
Bank and SBA applications add tax returns, profit-and-loss statements, and often a business plan. If a lender asks for far more than this list for a small revenue-based advance, that is a sign to compare offers elsewhere.
Mistakes That Cost Columbus Businesses Real Money
Borrowing for a slow season with a fast product. Daily-debit funding is built for needs that generate cash quickly — an event surge, a big order, a seasonal inventory buy. Using it to cover a structural loss just stacks payments on top of a shortfall.
Signing on total repayment you never saw. Always get the total repayment dollars in writing before you sign — not just the factor rate or the monthly estimate. Two offers with the same advance amount can differ by thousands in total repayment.
Applying everywhere at once. Multiple applications in the same week can signal distress to funders. Apply through one broker who shops multiple funders, and compare the actual offers side by side.
Ignoring the lease. For a restaurant or retailer, the lease is the business: a short remaining term or a landlord who will not approve an assignment can kill an expansion plan. Sort the lease before you borrow for the build-out.
Frequently Asked Questions
How fast can a Columbus business get funded? Revenue-based products decide in hours and fund in 24–72 hours once statements are in. Equipment financing takes days to a couple of weeks. SBA products take a month or more.
Do I need a voided check or photo ID to apply? No — not to see offers. Bank statements and an application are the standard ask. A voided check or photo ID is sometimes requested for verification on specific products before funding, but neither is a universal upfront requirement.
What credit score do I need? Revenue-based funders weight bank deposits far more heavily than credit score, and scores in the 500s routinely get funded. SBA and bank products are stricter, typically 650-plus.
Does the university calendar really change funding demand? Yes, for campus-adjacent businesses. Student traffic, move-in weekends, home football Saturdays, and graduation season create real surges for restaurants, retailers, and service firms near Ohio State — and real troughs in between. Funders who understand that calendar price the file better than those who average it away.
Can a new Columbus business get funded? A pre-revenue startup leans on SBA loans or a term loan underwritten on the owner's credentials and business plan, not on bank statements that do not exist yet. Revenue-based products need 3–6 months of deposits, so they come after opening, not before.
Columbus businesses: get your numbers in 24 hours
Tell us about your business and send your last 3 months of statements — we will compare multiple funders and put total repayment dollars in writing. No obligation, no upfront fees, no voided check required to see your offers.
Start your application or call (352) 809-3201
Ready to Get Funded?
Apply now and get a funding decision within hours. No hard credit pull for pre-approval — see your options risk-free.