Fast Business Funding in Corpus Christi, TX: the $7.25 Wage Floor, a 203-Million-Ton Port & the 4.3% Unemployment Rate (2026)
Corpus Christi pairs the lowest wage floor in the country — $7.25 an hour, less than half of California's — with the third-largest port in the United States, moving 203.4 million tons of cargo in 2025. The city held 317,247 people in July 2025, unemployment was 4.3 percent in September 2026, and the port, the refineries, the naval air station, and the hospitals keep business-to-business demand moving year-round. Here is how business funding actually works in the Corpus Christi market: the product map by business type, real timelines, the grants and loan programs that exist, and how to compare offers.
Need funding fast? Apply in about 2 minutes — get a decision within hours, with no hard credit pull for pre-approval.
Apply Now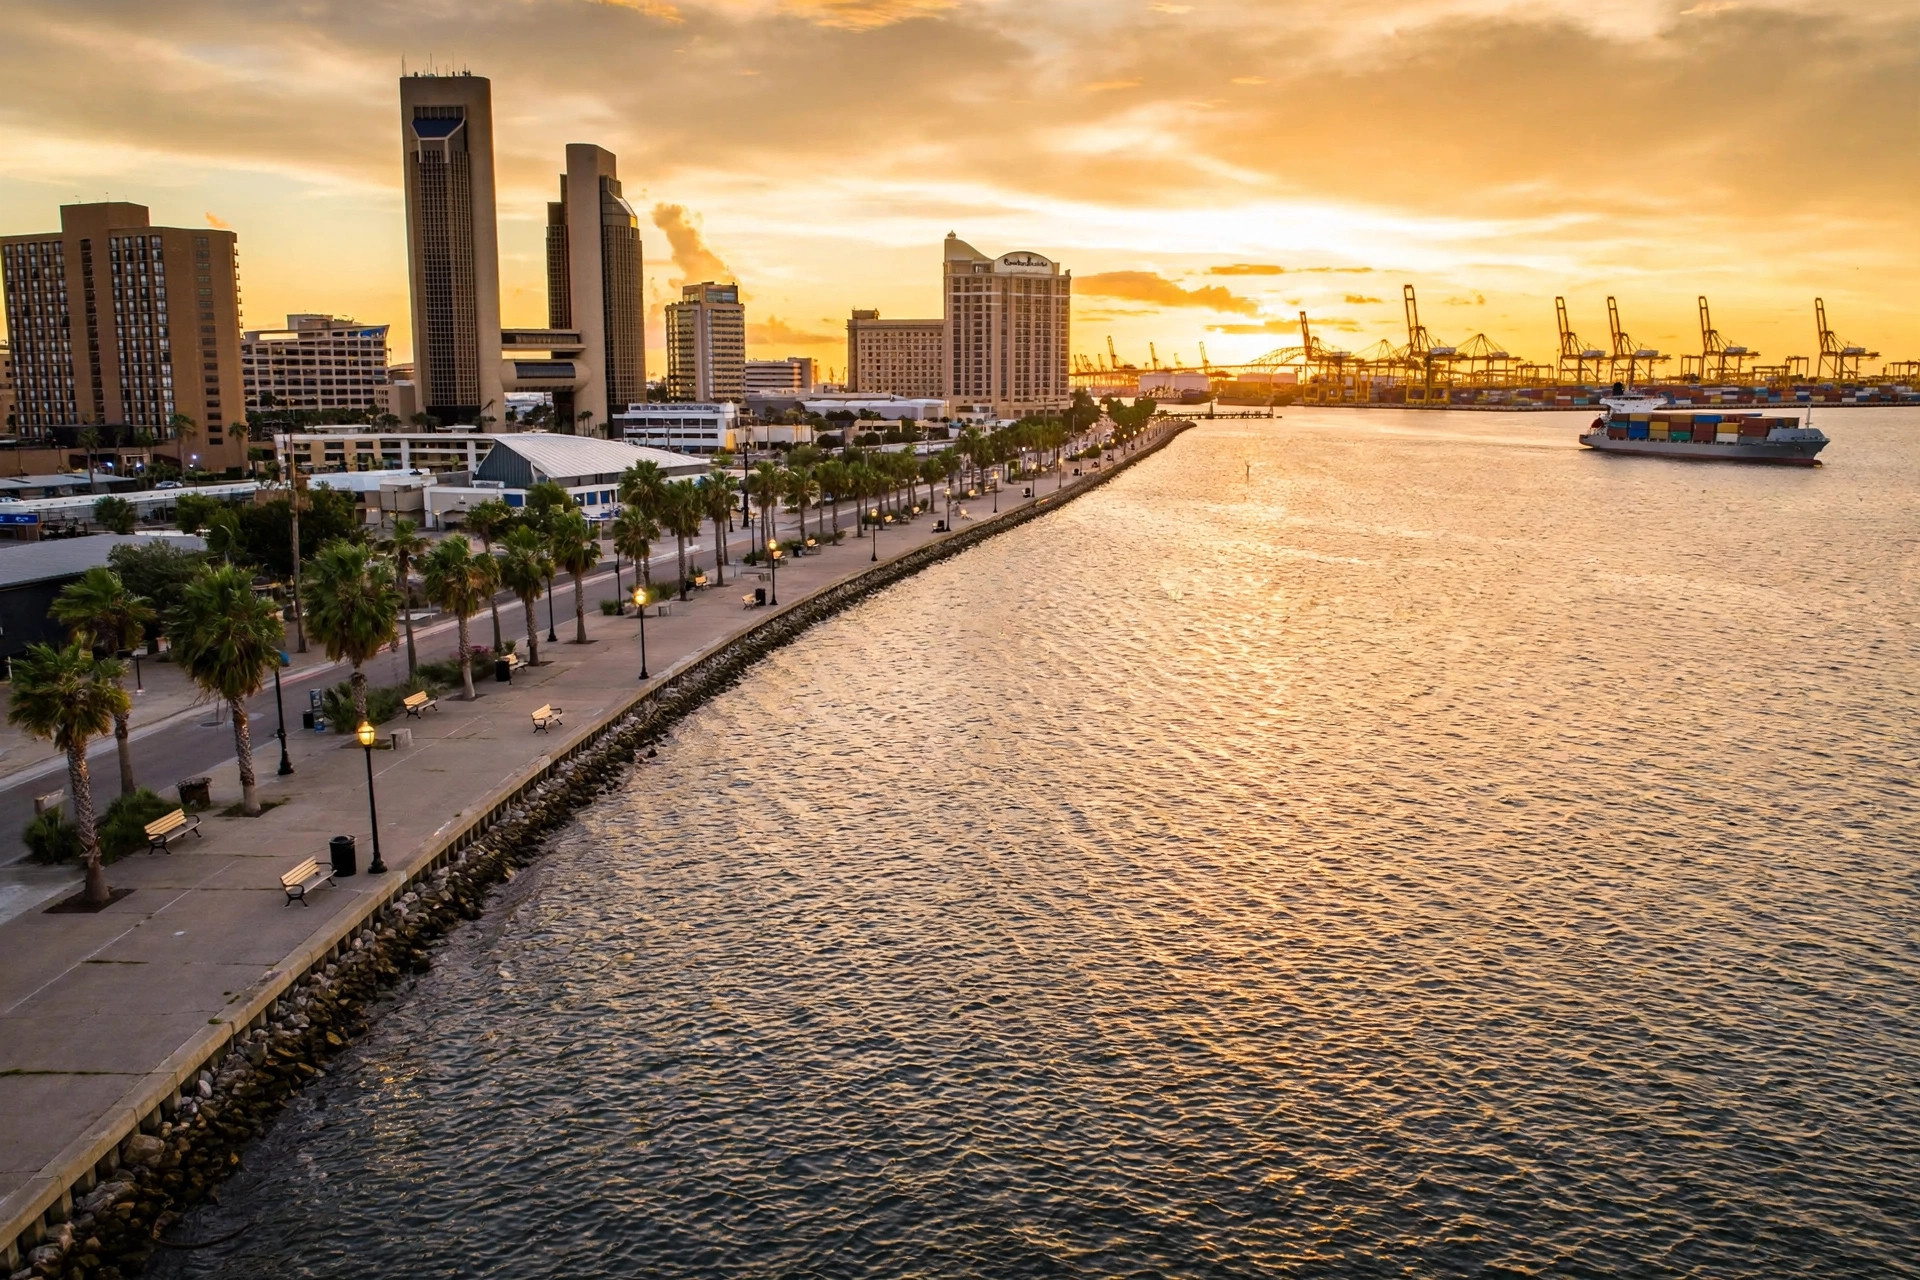
Key Takeaways
- Corpus Christi has no local minimum wage — Texas adopts the federal floor of $7.25 an hour, unchanged since 2009, and state law bars cities from setting a higher one for private employers. Twelve staff at the floor cost $3,480 a week; the same twelve in California cost $8,112 a week. The wage floor is the cheapest line item in a Corpus Christi budget — and the reason a funder looks at your actual payroll, not the statute, when pricing a file.
- The city unemployment rate was 4.3 percent in September 2026 — against 4.4 percent statewide and 4.2 percent nationally — with the Corpus Christi metro at 4.5 percent. Hiring is not the constraint in Corpus Christi; the constraint is the energy cycle. A business that can show steady deposits through a soft crude quarter prices better than one that cannot.
- Corpus Christi itself held 317,247 people on July 1, 2025 — essentially flat against 317,863 counted in the 2020 census — with a median household income of $67,394 and per capita income of $34,788, across 118,741 households. It is the eighth-largest city in Texas and the regional hub for medical services across South Texas.
- The Port of Corpus Christi moved 203.4 million tons of cargo in 2025, making it the third-largest port in the United States by total waterborne tonnage. Crude oil was 127.4 million tons of that total, LNG was 18.6 million tons and up 15.4 percent, and crude exports run at roughly 2.3 to 2.5 million barrels a day — about half of all crude the United States exports. The second quarter of 2026 was a record at 55.8 million tons, and the first nine months of 2026 were the strongest nine-month period in the port's history.
- The biggest employers are the hospital, the school district, and the base: CHRISTUS Spohn Health System at 7,866 people, Corpus Christi ISD at 5,795, and Naval Air Station Corpus Christi at 5,000 — the Texas Comptroller counts 7,110 direct jobs at the station including 1,917 active-duty military, and 20,530 direct and indirect jobs in total. The Corpus Christi Army Depot on the station employs more than 3,600 civilians and is the largest helicopter repair facility in the world. Driscoll Children's Hospital employs 2,609 and Texas A&M University–Corpus Christi employs 2,363.
- The city pays real money, but it is narrow and specific: the City of Corpus Christi's Type B Small Business Assistance Program approved $1,226,750 for fiscal 2027, including a $75,000 LiftFund interest buy-down, $98,500 for SCORE advising, and $150,000 for the Del Mar College SBDC. LiftFund lends $500 to $1,000,000, PeopleFund lends up to $250,000, and the state Capital for Texas program lends $5,000 to $350,000. There is no general city cash grant for operating costs. SBA 7(a) loans run up to $5 million.
- Bank statements are the main document — gather three months before you start. For an energy, trucking, or marine-services business, bring the contract too: a funder that sees a signed port, refinery, or hauling contract prices the file very differently from one that only sees deposits.
Why Corpus Christi borrows differently
Most American cities have one economy. Corpus Christi has three, stacked on top of each other. The first is the port economy: the Port of Corpus Christi moved 203.4 million tons of cargo in 2025 — crude oil 127.4 million tons, LNG 18.6 million tons and up 15.4 percent — making it the third-largest port in the United States by total waterborne tonnage. Crude exports run at roughly 2.3 to 2.5 million barrels a day, about half of all the crude the United States exports, and the second quarter of 2026 set a record at 55.8 million tons. Around that throughput sits a whole trade economy: trucking, warehousing, marine services, fabrication, and equipment repair, whose revenue follows the shipping calendar and the price of crude.
The second economy is energy and petrochemicals. The refineries and chemical plants along the ship channel have drawn about $20 billion of investment into local facilities, and their maintenance turnarounds, expansions, and shutdowns set the calendar for hundreds of contractors — welders, scaffolders, inspectors, industrial cleaners, staffing firms — whose revenue arrives in bursts tied to plant schedules. The third economy is the anchor institutions that never move: CHRISTUS Spohn at 7,866 people, the school district at 5,795, Naval Air Station Corpus Christi at 5,000, Driscoll Children's Hospital at 2,609, and Texas A&M University–Corpus Christi at 2,363. The base alone supports 20,530 direct and indirect jobs, and the Army Depot's 3,600-plus civilian workforce makes it the largest helicopter repair facility in the world and the largest industrial employer in South Texas.
The wage floor is the defining number for a borrower — because in Corpus Christi it is the lowest in the country. At $7.25 an hour, twelve staff cost $3,480 a week in base wages, or $15,080 a year each for one full-time worker. The same twelve staff in California cost $8,112 a week at the $16.90 floor. That gap is the whole story of a Corpus Christi payroll: the statute sets almost nothing, and the market sets everything. A refinery contractor, a hospital supplier, and a restaurant on the bayfront pay wildly different wages for the same twelve headcount, and lenders underwrite the payroll you actually run, not the $7.25 floor. A file that shows a $3,480-a-week payroll when the business actually runs twice that reads as careless — and a funder that prices on the real number is the one you want.
The second defining number is the customer base. A median household income of $67,394 — below the Texas median of $78,476 — means Corpus Christi's restaurants, retailers, and service firms sell into a working-class coastal market of 317,247 people, and the port, the refineries, and the base keep business-to-business demand moving even when consumer spending is soft. The honest counterweight is the energy cycle: a soft crude price, a delayed turnaround, or a slow shipping quarter moves contractor revenue, and contractor revenue moves the suppliers and repair shops that borrow against it. Funders know this, and a file that pretends otherwise reads as naive. The businesses that borrow well in Corpus Christi are the ones that show the funder the other side of the ledger: a signed contract, a diversified client list, a book of recurring revenue. Deposits plus a contract beat deposits alone, every time.
The Corpus Christi funding map: which product fits which business
Funding is not one product. The right one depends on what the money is for, how fast it comes back, and what your revenue looks like month to month. Here is the map for Corpus Christi:
Merchant cash advance — for card-heavy businesses with a short-term gap. Restaurants, retailers, and service firms with steady card sales borrow against future receipts and repay daily or weekly as a share of sales. A $50,000 advance at an illustrative 1.20 factor rate repays $60,000 in total — $10,000 of cost — or about $2,308 a week over 26 weeks. The advance is fast, usually 24 to 72 hours, and it flexes with a slow week. It is the most expensive money on this map, and it is the right call only when the money comes back within months.
Term loan — for a known cost with a fixed payoff date. A work truck, a welding rig, a marine-services build-out, a hire that pays for itself over a year. Fixed daily, weekly, or monthly payments over months to years, priced on a rate or a factor depending on the lender. If the spend has a clear return date, match the term to it — borrowing for 12 months to pay for something that returns in 12 weeks is overpaying.
Business line of credit — for the lumpy business. An energy contractor, a trucking company, or a marine-services firm with revenue that arrives in bursts draws only what it needs and pays interest only on what it draws. The line is the right tool when the gap is timing — a turnaround payment 60 days out, a contract that pays quarterly — rather than a single purchase. Draws after approval are typically same-day.
Equipment financing — for the thing itself. A crane truck, a forklift, a fabrication line. The equipment secures the loan, so the pricing is usually the cheapest money on this map for an asset purchase, and the term can run two to five years. If the money buys a thing, price the equipment product first.
SBA and guaranteed loans — for the cheapest money, if you can wait. SBA 7(a) loans run up to $5 million through SBA lenders. The underwriting is real and the clock runs weeks, not days — but for a build-out or a refinance, the rate difference is worth the wait.
Grants and loan programs: what actually exists in Corpus Christi
Before you borrow, check the money that does not need repaying — and be honest about what is open right now. Corpus Christi pays real money, but it is narrow and specific, not a general cash grant. The city's Type B Small Business Assistance Program approved $1,226,750 for fiscal 2027, including a $75,000 LiftFund interest buy-down program, $98,500 for SCORE business advising, $199,500 for a Texas A&M University–Corpus Christi internship program, $150,000 for a Del Mar College internship program, and $150,000 for the Small Business Development Center. In fiscal 2025 the LiftFund buy-down put 10 loans out totaling $281,596, with $92,226 in interest buy-down funds. There is no general city cash grant for operating costs.
The lending channel is the nonprofit one. LiftFund, a nonprofit community development lender based in San Antonio that lends in Corpus Christi, offers small-business loans from $500 to $1,000,000 over 1 to 15 years, with rates as low as 0 percent in partner-city programs. PeopleFund, another nonprofit lender, lends up to $250,000 for equipment, working capital, and lines of credit, and up to $5 million through SBA programs — it has no Corpus Christi office, but it lends statewide. The state-run Capital for Texas program, run with PeopleFund, LiftFund, and BCL of Texas, lends $5,000 to $350,000 to businesses in smaller communities. The bigger channel is the federal one. SBA 7(a) loans run up to $5 million through SBA lenders, and SBA 504 loans run up to $5.5 million for owner-occupied real estate and long-life equipment. The Del Mar College SBDC, at 3209 South Staples Street in Corpus Christi, offers free one-on-one advising and loan-packaging help year-round — call (361) 698-1021 — and it is the front door for most state and federal programs.
The money that does reach operating businesses beyond storefronts and loan guarantees is statewide and national. The Amber Grant for Women pays $10,000 grants every month to women-owned businesses nationwide, including in Texas. The Texas Enterprise Fund is a state deal-closing grant, but it is for large expansions only — more than 75 new full-time jobs in an urban area — and is not a small-business program. Grants are slow and competitive, and none of them cover payroll next Friday. Use them for the project they fit, and borrow for the gap they leave — not the other way around.
Timelines: how fast the money actually lands
Speed is a real product feature in Corpus Christi, because the city's costs do not wait. A merchant cash advance from an online lender funds in 24 to 72 hours after approval, with three months of bank statements as the core document. A term loan from an online lender runs a similar clock, a day or two slower for larger amounts. A business line of credit decides in minutes to a day, and draws after that are same-day. SBA loans take weeks — sometimes six to eight — because the underwriting is real and the guarantee is federal. Equipment financing sits in the middle: days to a couple of weeks, depending on the vendor and the amount. The city's own grant and loan programs run slower still — they are low-cost capital, not fast capital, and the application goes through the city's economic development channel or the SBDC.
What slows a file down is almost never the lender. It is the missing document: a bank statement with a gap, a business license that lapsed, a second owner's signature that was never collected. Gather three months of statements, a photo ID, and a voided check before you apply — the ID and the check are usually optional, not required, but having them ready removes the stall. If you have an advance outstanding already, disclose it upfront: underwriters find it anyway, and a stacked file quotes worse when it is discovered than when it is declared.
How to compare two Corpus Christi offers
Get both offers on the same amount, in writing, with the same three numbers: the total dollars repaid, the payment frequency and amount, and every fee. A $100,000 advance at a 1.10 factor repays $110,000; at 1.25 it repays $125,000 — a $15,000 spread on the same money. The factor is not the whole story either: an origination fee deducted from proceeds changes what actually lands in your account, and a daily repayment schedule bites harder than a weekly one on the same total. The cheapest offer is the smallest total repaid on a schedule your slowest week can carry. If a lender will not put the total in writing, that is your answer about the lender.
For Corpus Christi files specifically, ask one more question: does the funder understand the energy cycle? A refinery contractor, a marine-services firm, or a trucking company has lumpy months tied to turnaround schedules and crude prices — and a funder that prices the file on one slow month alone will quote you like a failing business. A file that shows twelve months of deposits, the signed contract, and the explanation for the slow month gets priced like the business it is.
Frequently asked questions
What is Corpus Christi's minimum wage in 2026? Corpus Christi has no local minimum wage, and Texas has no state rate above the federal floor — so $7.25 an hour applies, unchanged since 2009. State law bars Texas cities from setting a higher minimum for private employers. Twelve staff at the floor cost $3,480 a week, but most Corpus Christi employers pay well above it — the market, not the statute, sets the payroll.
How fast can a Corpus Christi business get funded? A merchant cash advance typically funds in 24 to 72 hours after approval with three months of bank statements. Term loans run a similar clock, lines of credit decide in minutes to a day, equipment financing takes days to a couple of weeks, and SBA loans take weeks. The city's own grant and loan programs run slower.
Are there grants for Corpus Christi small businesses in 2026? Yes — but narrow ones. The city's Type B program approved $1,226,750 for fiscal 2027, including a LiftFund interest buy-down, SCORE advising, and SBDC funding. LiftFund lends $500 to $1,000,000, PeopleFund lends up to $250,000, and the state Capital for Texas program lends $5,000 to $350,000. There is no general city cash grant for operating costs. The Amber Grant pays $10,000 a month to women-owned businesses nationwide.
What do I need to apply? Three months of business bank statements are the core document. A photo ID and a voided check are usually optional verification, not requirements — but having them ready removes stalls. Energy, trucking, and marine-services businesses should also bring the contract; restaurants and retailers should bring the lease.
Does the energy cycle hurt my approval chances? Funders underwrite your business, not the headlines — but they do know the market. A contractor or marine-services file with steady deposits, signed contracts, and an explanation for any slow month prices far better than a file that leaves the funder to guess. Show the contract and twelve months of deposits, not just the last quarter.
Can a trucking or marine-services business get funded in Corpus Christi? Yes — trucking, marine services, and fabrication are among the most common Corpus Christi profiles, because the port keeps freight moving year-round and the refineries keep contractors busy. An advance fits a short-term fuel or payroll gap; equipment financing is usually the cheapest route for a truck or a crane; and LiftFund or an SBA loan can fill a gap a bank will not cover on its own.
Ready to fund your Corpus Christi business?
One application, competing offers, total cost in writing. Bank statements are the main document — gather three months before you start, and bring the contract if you are in energy, trucking, or marine services, or the lease if you are a restaurant or retailer.
Apply Now or call (352) 809-3201
Ready to Get Funded?
Apply now and get a funding decision within hours. No hard credit pull for pre-approval — see your options risk-free.