Fast Business Funding in Kailua, Hawaii: MCA & Small Business Loans (2026)
Kailua's small businesses pay Hawaii's real cost of doing business — and they can't wait 90 days for a bank answer. MCA, term loans, and lines of credit for Kailua merchants: what fast funding actually means, the freight-cost reality that shapes every offer, and how to compare funders.
Need funding fast? Apply in about 2 minutes — get a decision within hours, with no hard credit pull for pre-approval.
Apply Now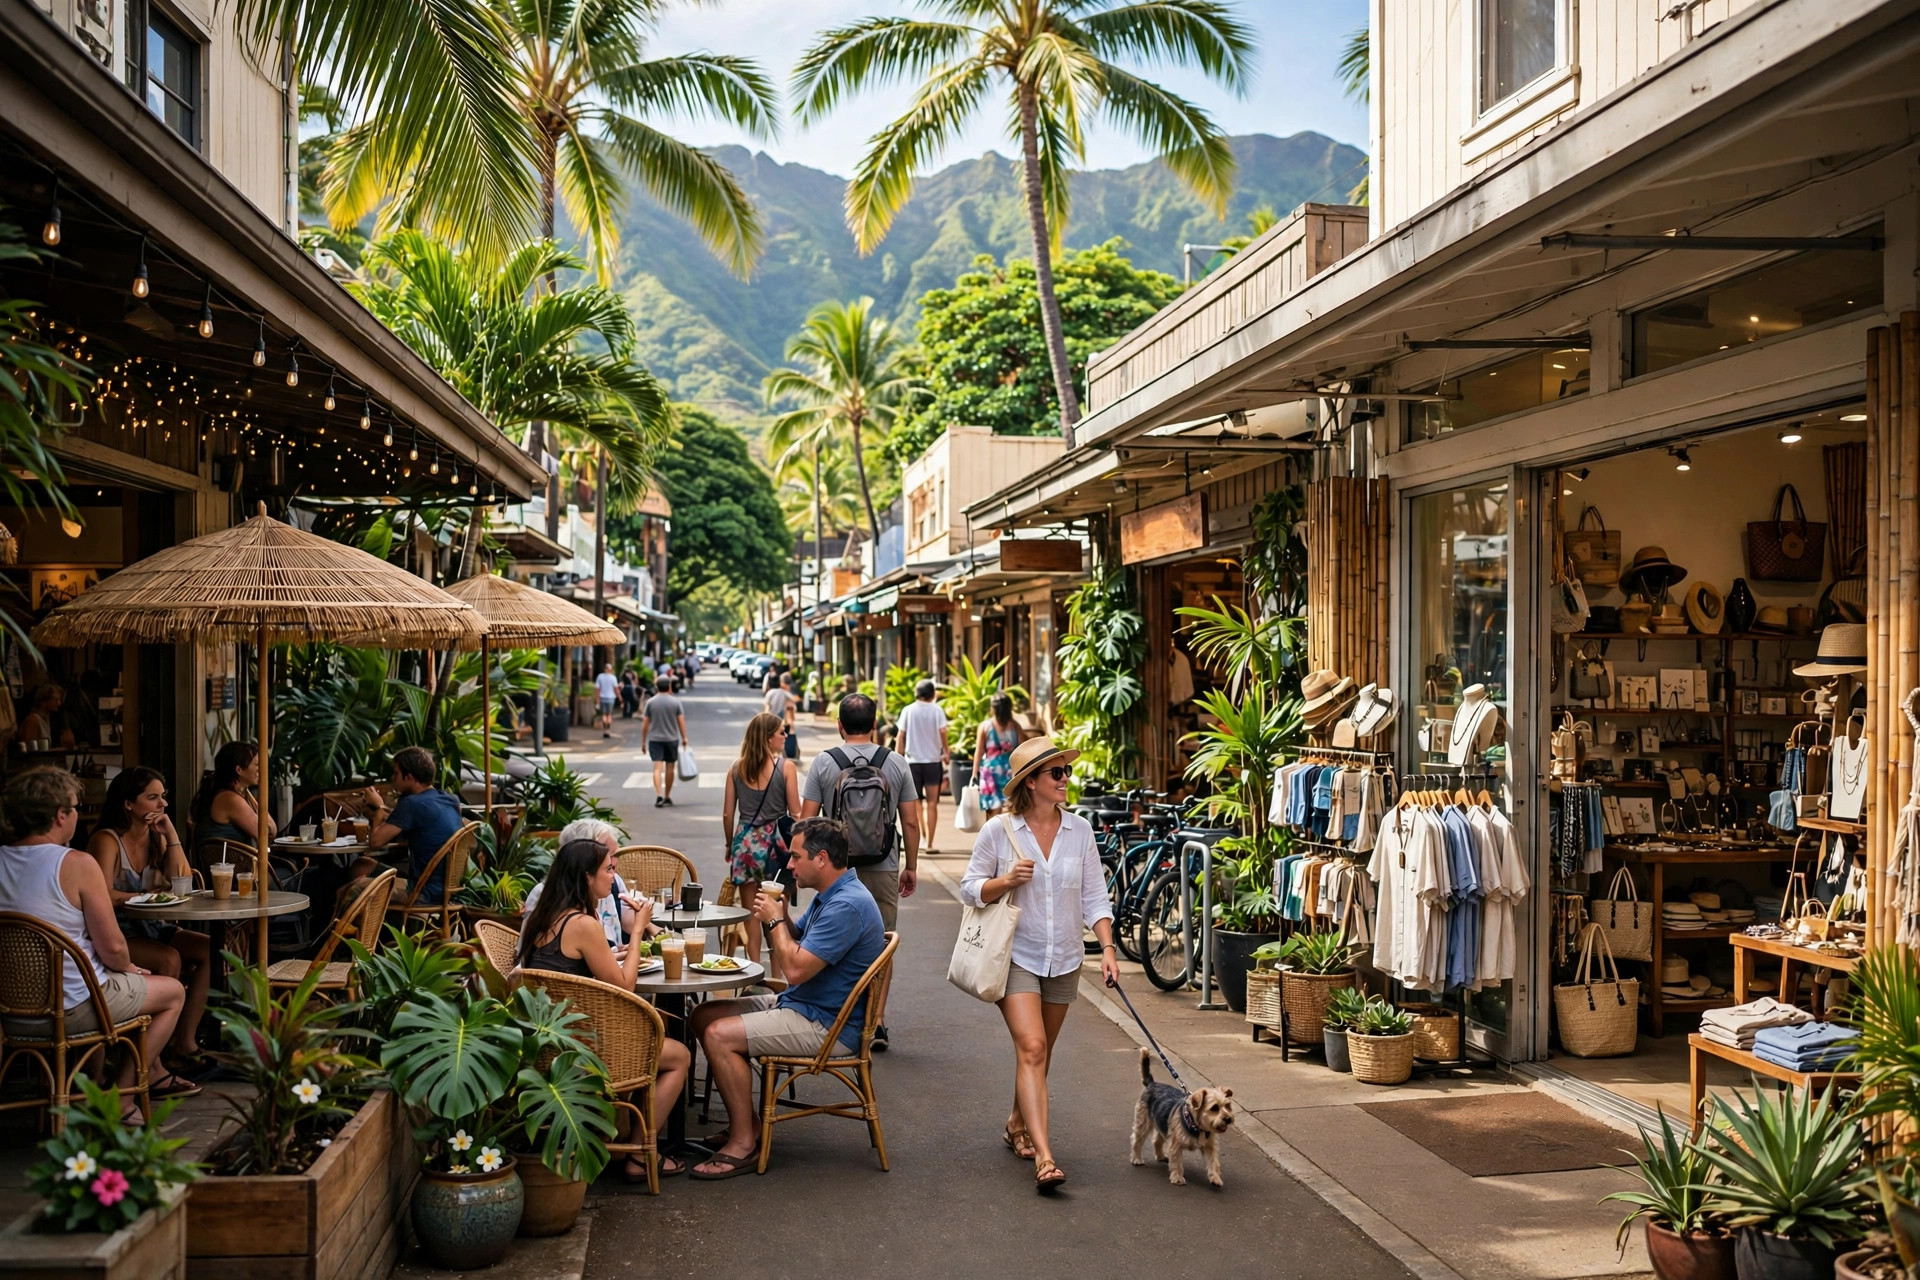
Key Takeaways
- Alternative lenders decide in hours and fund in 24–72 hours for Kailua businesses; banks typically take 30–90 days for the same money.
- Hawaii's inter-island freight rates rose 25.75% effective January 1, 2026 — and shipping costs are up roughly 80% in five years — which means Kailua merchants should size working-capital requests around real supply costs, not last year's numbers.
- The MCA is the speed product (24 hours), short-term term loans balance cost and speed (1–3 days), and lines of credit win for repeat inventory needs.
- The one document every Kailua funder requires is 3 months of business bank statements — photo ID and voided checks are optional verification, never upfront requirements.
Kailua looks like a sleepy beach town, but its economy is all small business. The walkable town center — Kailua Road, Ku'ulei Road, and the blocks in between — runs on independent restaurants, coffee houses, boutiques, jewelry shops, and local designers drawing both residents and the steady stream of visitors coming off Kailua Beach. Analysts estimate roughly a third of the retail traffic in Kailua comes from visitors, well above the norm for neighborhood retail elsewhere on Oahu — a tourist-season lift most merchants build their year around.
And Hawaii taxes that economy twice: once for living on an island, and again for moving goods between islands. Everything a Kailua restaurant serves, a contractor builds with, or a boutique stocks arrives over a supply chain with no shortcuts — which is exactly why working capital is the lifeblood of this market. This guide covers what "fast funding" actually means for a Kailua business, which products fit which situations, the Hawaii-specific cost rule that should change how you size a request, and how to shop a funder the way a funder shops you.
What "fast funding" actually means in Kailua
Speed is two things — how fast you get a decision, and how fast money lands. Here's what Kailua merchants see across products in 2026:
| Product | Typical decision | Typical funding |
|---|---|---|
| Merchant cash advance | 2–4 hours | Same day to 24 hours |
| Short-term term loan | Same day to 1 day | 1–3 business days |
| Business line of credit | 1–2 days | 2–5 business days |
| Invoice factoring | 1–2 days | 2–4 business days |
| Equipment financing | 1–3 days | 3–7 business days |
| SBA 7(a) loan | 30–90 days | 60–120 days |
The line is the same in every market: anything touching a bank credit committee or an SBA guarantee adds weeks. If you need money this month, you're choosing among the top five rows — and the right one depends on what you're buying.
The options, ranked by speed
1. Merchant cash advance — fastest, for revenue you can see
The MCA turns tomorrow's deposits into cash today. Underwriting is statement-based — 3 to 6 months of bank activity, priced off monthly revenue, no collateral appraisal, no credit committee. Most Kailua files we run on MCAs fund the day after approval.
The trade: it's the most expensive capital per dollar. Factor rates of 1.30–1.45 on daily or weekly debits are the typical range for a healthy file. Before you take one, read how much a merchant cash advance actually costs so you know the math cold.
2. Short-term term loan — the cost/speed balance
Funders who lend (rather than advance against receivables) move nearly as fast on clean statements — same-day decisions are real — but they look harder at time in business and credit. Terms run 6–24 months with weekly or monthly payments. For a Kailua contractor financing a materials purchase ahead of a renovation job, this is usually the sweet spot.
3. Business line of credit — the repeat-need winner
Slower to open (a few days) but the cheapest draw you'll make all year once it's in place. Retailers restocking between visitor seasons and restaurants absorbing food-supply cost swings stop re-applying every season.
4. Invoice factoring — for the contractors and suppliers
Kailua's windward side is renovation and remodel country — aging homes, high property values, and constant kitchen-and-bath work. Revenue in those trades sits in 30-day receivables before it sits in the bank. Factoring turns invoiced work into this week's payroll.
5. SBA 7(a) — the cheapest money, on the slowest clock
Still the lowest-cost capital a small business can get, but 60–120 days to funding is real. If you're planning a 2027 expansion, start the SBA conversation now — it doesn't solve a 2026 emergency.
Hawaii's one rule you should actually know: freight is a working-capital line item
Almost everything a Kailua business sells or uses arrives on a barge — first across the Pacific, then between islands. Hawaii has one regulated inter-island carrier, and effective January 1, 2026 its freight rates rose 25.75% under a permanent rate structure approved by the state's Public Utilities Commission, replacing a temporary 18% increase. That followed a 46% increase in 2020 — inter-island shipping costs are up roughly 80% in five years — and the PUC locked the new rates in as the baseline through at least early 2028.
Practical translation for a Kailua merchant: your cost of goods keeps compounding while your funding math stands still. A restaurant's food-supply budget, a contractor's materials line, a boutique's inventory restock — all of it got materially more expensive on January 1, and every raise flows through the whole chain until it reaches the customer. When you size a working-capital request, build it on 2026 landed costs, not 2024 numbers:
- Ask for the freight line explicitly. Don't lump supply costs into a vague "working capital" number — funders underwrite better when they see what the money actually buys, and your own numbers stay honest.
- Size inventory loans for the real restock. If your restock cost rose 25% with the freight structure, a loan sized off old invoices runs out before the season does.
- Contractors: pre-buy materials when the job is won. A short-term term loan against a signed contract beats buying in smaller, more expensive lots as freight surcharges keep layering on.
See how to tell a legit funder from a scam for the full pre-signing checklist.
Kailua funding reality, by corridor
- Kailua Town (Kailua Road / Uluniu Street): The walkable heart — brunch spots, coffee houses, boutiques, jewelry shops. High foot traffic and visitor share means strong card revenue and fundable daily deposits; lease deposits and buildouts are the #1 use of funds when a space turns over.
- Ku'ulei Road corridor: The commercial strip where expansion happens — new restaurant and retail spaces opening alongside housing development. TI buildouts and equipment packages are the typical ask here, and funders like the revenue density.
- Beach-adjacent visitor businesses: Surf shops, rental operators, and eateries near Kailua Beach ride the visitor third of traffic. Revenue peaks follow visitor seasons, so lines of credit (draw in the slow months, repay in the busy ones) beat one-off advances for smoothing the curve.
- Windward residential communities (Aikahi, Enchanted Lake, Keolu Hills): Home services, remodelers, landscapers, and professional services. Bigger average deals, deeper files — the typical suburban contractor file funds in 24–48 hours on clean statements.
What every funder will actually ask for
The required document is the same at every funder in this market: your last 3 months of business bank statements. That's the MCA industry's universal underwriting file — statements, application, and a photo ID for identity verification on some products.
- Required: 3 months of business bank statements, a short application.
- Sometimes requested (verification, not upfront): a voided check or photo ID on specific products — never a precondition for seeing terms.
- Red flag: anyone demanding a voided check, ID, or "good faith deposit" before showing you numbers in writing. Walk away.
The 10-minute comparison drill
Take any two offers and run this before you sign anything:
- Total dollars out the door. Advance × factor rate + all fees. Write both numbers down. The smaller number wins unless the larger one has a real advantage (speed, term, renewal path).
- Daily/weekly debit as a share of revenue. If the debit exceeds roughly 10–15% of monthly revenue, the "fast" money becomes the cash-flow problem. Ask for the holdback percentage in writing.
- The fee stack. Origination, ACH, NSF, default — name them or they don't exist. Get them in the agreement, not in a phone call.
- The funder's name. Know who's actually funding you, not just who brokered it. Licensed funders say it plainly.
- The renewal path. If you perform, what's your second advance priced at? Good funders discount renewals — ask before the first deal, not after.
Frequently asked questions
How fast can a Kailua business actually get funded?
A merchant cash advance typically funds same-day to 24 hours after approval, and approvals run 2–4 hours on clean statements. Short-term term loans take 1–3 business days. Anything bank-issued (including SBA-backed) takes 30–120 days — that timeline is structural, not negotiable.
Does Hawaii cap MCA factor rates?
An MCA is structured as a purchase of future receivables, not a loan — priced with a factor rate, not an interest rate — so traditional state interest-rate caps aren't the framework that applies. Compare offers in total dollars repaid and get the figure in writing before you commit.
Can I get funding with bad credit in Kailua?
Yes — revenue-based products (MCA, invoice factoring) underwrite primarily on bank statements, not credit scores. Credit matters more for term loans and lines of credit. See your options with bad credit for the full breakdown.
What's the minimum revenue to qualify?
Most alternative funders want to see roughly $10,000–$15,000 in monthly deposits before the numbers work. Below that, the debit takes too big a share of cash flow and reputable funders will tell you to wait — which is itself a signal you're talking to the right people.
Why do Kailua businesses need more working capital than similar mainland businesses?
Supply chain. Nearly every input — restaurant ingredients, contractor materials, retail inventory — arrives over one of the most expensive freight networks in the U.S., and inter-island rates rose another 25.75% on January 1, 2026 with costs up roughly 80% over five years. That inflates cost of goods for the same revenue, which is exactly what working capital is for.
Kailua businesses: get your numbers in 24 hours
Tell us about your business and send your last 3 months of statements — we'll compare multiple funders and put total repayment dollars in writing. No obligation, no upfront fees, no voided check required to see your offers.
Start your application or call (352) 809-3201
Ready to Get Funded?
Apply now and get a funding decision within hours. No hard credit pull for pre-approval — see your options risk-free.