Fast Business Funding in Norfolk, VA: the World's Largest Naval Station, a 3.5M-TEU Port & a $66,109 Median Income (2026)
Norfolk pairs the world's largest naval station with the Port of Virginia — 3,499,639 TEUs in fiscal year 2024, the second-best year in port history — inside a Hampton Roads metro of about 1.80 million people. The city held 231,013 people on July 1, 2025, with a median household income of $66,109 and a 4.2 percent city unemployment rate in September 2026. Here is how business funding actually works in the Norfolk market: the product map by business type, real timelines, the state programs that exist, and how to compare offers.
Need funding fast? Apply in about 2 minutes — get a decision within hours, with no hard credit pull for pre-approval.
Apply Now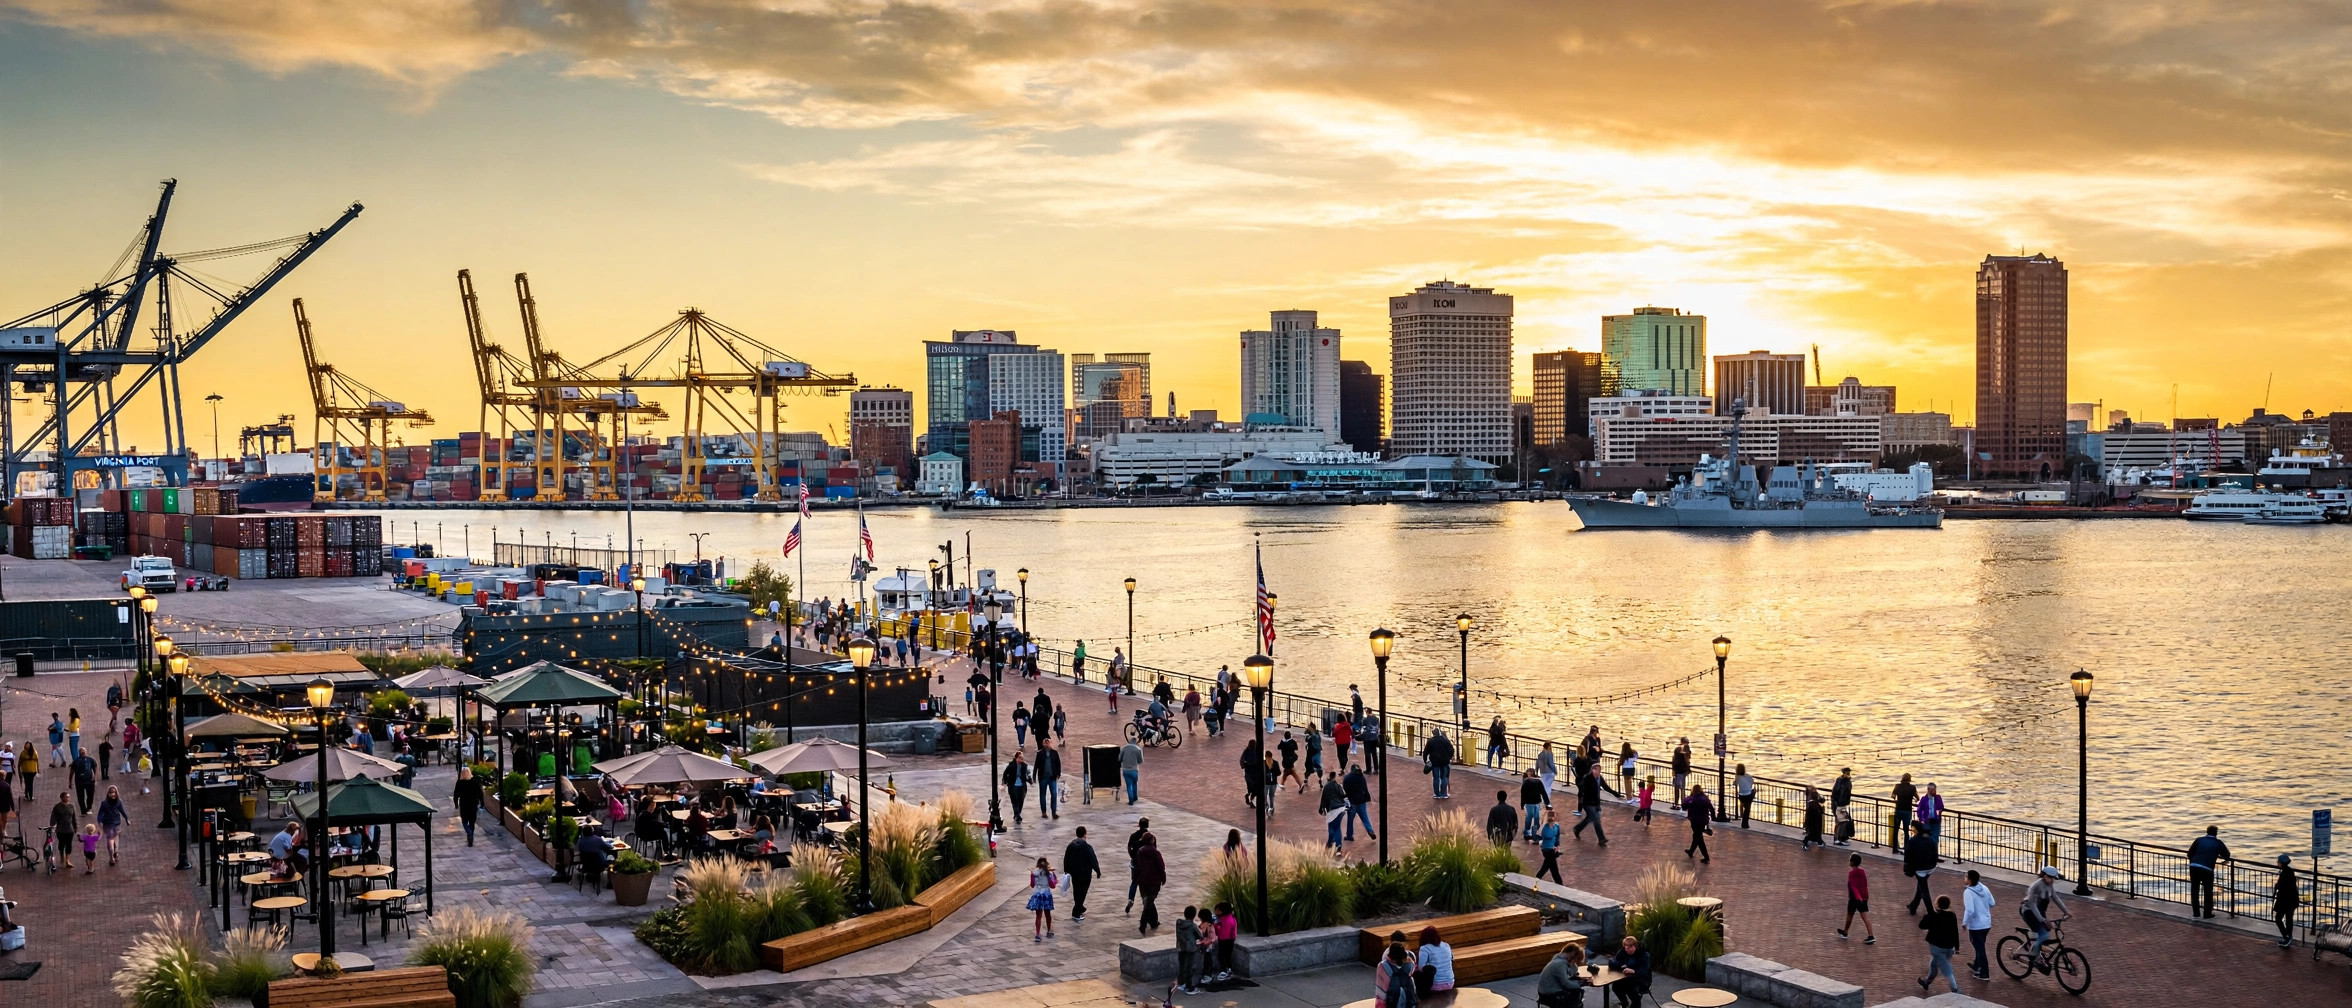
Key Takeaways
- Norfolk is a Navy town and a port town at the same time. Naval Station Norfolk is the world's largest naval station — about 75 ships, 14 piers, and more than 60,000 personnel on base every single day — and Norfolk International Terminals is the Port of Virginia's largest container terminal, moving 3,499,639 TEUs in fiscal year 2024.
- The port's scale is a statewide economic engine: a College of William & Mary study put the port's fiscal-year 2022 impact at more than 565,000 jobs and $63 billion in gross state product, and the channel is now 55 feet deep — the deepest on the U.S. East Coast.
- Norfolk held 231,013 people on July 1, 2025, down from the 2020 census count of 238,005, inside a Hampton Roads metro of about 1.80 million people. Median household income is $66,109, and city unemployment was 4.2 percent in September 2026. The city counted 5,398 employer establishments in 2023 and 16,438 nonemployer establishments in 2024.
- Defense work pays in lumps, not in a straight line. Navy maintenance availabilities and contract awards create uneven revenue for marine contractors and ship-repair subcontractors — BAE Systems' Norfolk yard won $555.1 million in Navy contracts between October 2025 and October 2026 — which is exactly the profile working-capital funding is built for.
- The cheapest money in Norfolk is public and specific: the Virginia Small Business Financing Authority's Microloan Program lends up to $150,000 directly, with no bank participation required, and its Loan Guaranty and Capital Connect programs help banks say yes when collateral is short. SBA 7(a) and 504 loans run to $5 million each.
Why Norfolk borrows differently
Most American cities have one economy. Norfolk has two, stacked on top of each other, and both of them pay in lumps. The first is the Navy. Naval Station Norfolk is the world's largest naval station — home port of the U.S. Atlantic Fleet, with 14 piers, about 75 ships, and roughly 134 aircraft — and more than 60,000 sailors and civilians pass through the gates every day. Norfolk also hosts NATO's Allied Command Transformation, the only NATO headquarters in North America, with about 750 personnel. Around the base sits a whole economy of defense contractors, ship-repair subcontractors, moving and storage companies, and service businesses that live on military families. The work follows Navy maintenance schedules: a contract is awarded, a ship comes in for an availability, a crew works around the clock — and then the yard goes quiet until the next award. A funder that prices the file on one quiet month alone will quote you like a failing business. A file that shows twelve months of deposits, the contract, and the explanation for the slow month gets priced like the business it is.
The second economy is the port. Norfolk International Terminals is the Port of Virginia's largest container terminal, and the port moved 3,499,639 TEUs in fiscal year 2024 — its second-best year ever, behind only the 3.7 million TEUs of fiscal year 2022. The port's own October 2026 numbers show the growth continuing: 279,202 total TEUs in the month, up 3.7 percent year over year, with loaded imports up 15.5 percent. A College of William & Mary study put the port's fiscal-year 2022 impact at more than 565,000 jobs statewide and $63 billion in gross state product. The channel is 55 feet deep, the deepest on the U.S. East Coast, and the North Berth modernization finishing in spring 2027 will push terminal capacity to 3.6 million TEUs a year. Trucking, warehousing, logistics, and marine-service firms borrow against receivables and equipment in a rhythm set by the ships, not by the calendar quarter.
The third economy is the one people see on the street: healthcare, higher education, and the visitor economy. Sentara Health is headquartered in Norfolk with about 30,000 employees system-wide, and Sentara Norfolk General Hospital is Hampton Roads' only Level I Adult Trauma Center. Old Dominion University enrolled 23,469 students in fall 2025, and Norfolk State University is a public HBCU in the city. Downtown, Ghent, the NEON District, and Ocean View hold the small-business corridors — restaurants, bars, boutiques, and galleries selling into a city of 231,013 people inside a metro of about 1.80 million, with a median household income of $66,109. Tourism adds its own season: VisitNorfolk put travel and tourism's fiscal-year 2025 impact on the city at $84.2 million, and the summer PCS season — military families moving in and out of Hampton Roads from mid-May through mid-September — is the busiest stretch of the year for moving, storage, and housing-service businesses.
One thing to get straight before you borrow on a Norfolk address: Norfolk Naval Shipyard is not in Norfolk. It is across the river in Portsmouth, despite the name — and Newport News Shipbuilding is in Newport News. Norfolk's own yards are BAE Systems Norfolk Ship Repair, a 109-acre facility on the Elizabeth River, General Dynamics NASSCO–Norfolk, and Colonna's Shipyard. A funder that confuses the two cities will misread your file. Show the contract and the yard, not the headline.
The Norfolk funding map: which product fits which business
Funding is not one product. The right one depends on what the money is for, how fast it comes back, and what your revenue looks like month to month. Here is the map for Norfolk:
Merchant cash advance — for card-heavy businesses with a short-term gap. Restaurants, retailers, and hospitality firms in downtown, Ghent, and Ocean View with steady card sales borrow against future receipts and repay daily or weekly as a share of sales. A $50,000 advance at an illustrative 1.20 factor rate repays $60,000 in total — $10,000 of cost — or about $2,308 a week over 26 weeks. The advance is fast, usually funded in 24 to 72 hours, and it fits a payroll gap or an inventory buy that pays back in a season. It is the most expensive money on this map, and it is the right call only when the money comes back within months. Read what actually happens if you default on an advance before you sign one, and read whether a merchant cash advance is legal for the state-by-state picture.
Term loan — for a known cost with a fixed payoff date. A work truck for a logistics firm, a marine contractor's equipment, a restaurant build-out, a hire that pays for itself over a year. Fixed daily, weekly, or monthly payments over months to years, priced on a rate or a factor depending on the lender. If the spend has a clear return date, match the term to it — borrowing for 12 months to pay for something that returns in three is overpaying for speed you do not need.
Business line of credit — for the lumpy business. A marine contractor waiting on a Navy availability payment, a logistics firm between receivables, or a hospitality business between seasons draws only what it needs and pays interest only on what it draws. The line is the right tool when the gap is timing — a contract 60 days out, a season that pays in September — rather than a single purchase. Draws after approval are usually same-day.
Equipment financing — for the thing itself. A crane, a delivery fleet, a commercial kitchen, a marine vessel's outfitting, medical equipment. The equipment secures the loan, so the pricing is usually the cheapest money on this map for an asset purchase, and the term can run two to five years. If the money buys a thing, price the equipment product first.
Purchase-order and invoice financing — for the contract economy. A defense subcontractor with a signed Navy contract or a logistics vendor with outstanding invoices can borrow against the order or the receivable instead of against future card sales. The advance is sized on the contract, not on last month's deposits, which is exactly the profile a contract business needs. Ask about it before you take a general-purpose advance.
SBA and guaranteed loans — for the cheapest money, if you can wait. SBA 7(a) loans run up to $5 million through SBA lenders, and SBA 504 loans run up to $5 million for owner-occupied real estate and long-life equipment. SBA microloans run up to $50,000. The underwriting is real and the clock runs in weeks, sometimes six to eight, but the rate is the lowest on this map. For the full comparison method, see which funding product fits which business.
Grants and loan programs: what actually exists in Norfolk
Before you borrow, check the money that does not need repaying — and be honest about what is open right now. Norfolk pays real money, but it is narrow and specific, not a general cash grant. The Virginia Small Business Development Center network offers free one-on-one counseling — the Hampton Roads SBDC serves Norfolk — and SCORE Hampton Roads offers free volunteer mentoring and workshops. Start there before you apply anywhere else — it costs nothing and it is the fastest way to a fundable file.
The state channel is the Virginia Small Business Financing Authority (VSBFA), the financing arm of the Virginia Department of Small Business and Supplier Diversity. Its Microloan Program lends up to $150,000 directly to the business — no bank participation required — for business acquisition, equipment and fixed-asset purchases, and working capital, with a $150 one-time application fee. Its Capital Connect Program participates in loans alongside companion small-business loans from lenders, its Classic Loan Guaranty Program guarantees a bank loan or line of credit when the bank needs added support to approve, and its Cash Collateral Program pledges cash collateral with participating lenders to cover collateral shortfalls. The VSBFA is the program to check first if a bank has already said no on collateral grounds — a guarantee can turn that no into a yes without changing the business.
The federal channel is the SBA itself: 7(a) loans to $5 million, 504 loans to $5 million for real estate and long-life equipment, and microloans to $50,000. The SBA's Richmond District Office serves Virginia, and the Hampton Roads SBDC can walk you through the application before you file it.
One honest note about grants: grants are slow and competitive, and none of them cover payroll next Friday. Use them for the project they fit, and borrow for the gap they leave — not the other way around. And if your business is in Virginia Beach, the same state programs apply — the difference is the local channel, not the state one.
What to watch before you sign
There is no substitute for the total repayment in dollars, in writing, before you sign. Compare offers on that number, not on the headline rate or the monthly payment. If a funder will not put the total in writing, that is your answer about the funder.
The second thing to watch is the repayment rhythm. Daily debits against a defense contractor's account during a quiet month between availabilities can drain the account before the next contract payment lands. Ask for weekly payments instead of daily if your revenue is lumpy, and ask what happens if a debit fails — a funder that answers clearly is a funder that has done this before.
The third is stacking. A second advance taken to cover the first one's payments is how a manageable file becomes a default. If you already hold an advance, read how to refinance one before you stack another, and read how the early-payoff discount works if you are weighing paying one off early.
Frequently asked questions
How fast can a Norfolk business get funded? A merchant cash advance typically funds in 24 to 72 hours after approval with three months of bank statements. Term loans run a similar clock, lines of credit decide in minutes to a day, equipment financing takes days to a couple of weeks, and SBA loans take weeks. The state programs — the VSBFA Microloan and Loan Guaranty — run slower, because they move through review rounds, with approvals typically in 7 to 10 business days for smaller loans.
What do I need to apply? Three months of business bank statements are the core document. A photo ID and a voided check are usually optional verification, not requirements — but having them ready removes stalls. Defense subcontractors should also bring the contract or purchase order; logistics firms should bring the receivables aging; restaurants and retailers should bring the lease.
Are there grants for Norfolk small businesses in 2026? There is no general City of Norfolk cash grant for operating costs. The real public money is the VSBFA's: a Microloan of up to $150,000, loan guarantees, and loan participations through the Capital Connect program. The Hampton Roads SBDC and SCORE Hampton Roads offer free advising that costs nothing and makes a file fundable faster.
Does the Navy economy help or hurt my approval chances? It helps, if the file shows it. Funders underwrite your business, not the headline. A marine contractor with a signed contract, steady deposits, and an explanation for a slow month between availabilities prices far better than a file that leaves the funder to guess. Show the contract and twelve months of deposits, not just the last quarter.
Can a defense contractor or a port logistics firm get funded in Norfolk? Yes — marine contractors, ship-repair subcontractors, trucking and warehousing firms, and defense suppliers are among the most common Norfolk profiles, because the base and the port keep contracts and cargo moving year-round. An advance fits a short-term payroll or inventory gap; purchase-order financing fits a contract; equipment financing is usually the cheapest route for a truck or a machine; and a state loan or an SBA loan can fill a gap a bank will not cover on its own.
Ready to fund your Norfolk business?
One application, competing offers, total cost in writing. Bank statements are the main document — gather three months before you start, and bring the contract or purchase order if you are a defense subcontractor, or the receivables aging if you are a logistics firm.
Apply Now or call (352) 809-3201
Ready to Get Funded?
Apply now and get a funding decision within hours. No hard credit pull for pre-approval — see your options risk-free.