Fast Business Funding in Philadelphia: Center City, Fishtown & South Philly Capital (2026)
Philadelphia is Pennsylvania's largest city and the nation's sixth-largest — eds and meds, historic tourism, a booming restaurant corridor, and a 2026 semiquincentennial crowd all create distinct funding needs. What fast funding looks like in Philly, which product fits which need, and how to compare offers.
Need funding fast? Apply in about 2 minutes — get a decision within hours, with no hard credit pull for pre-approval.
Apply Now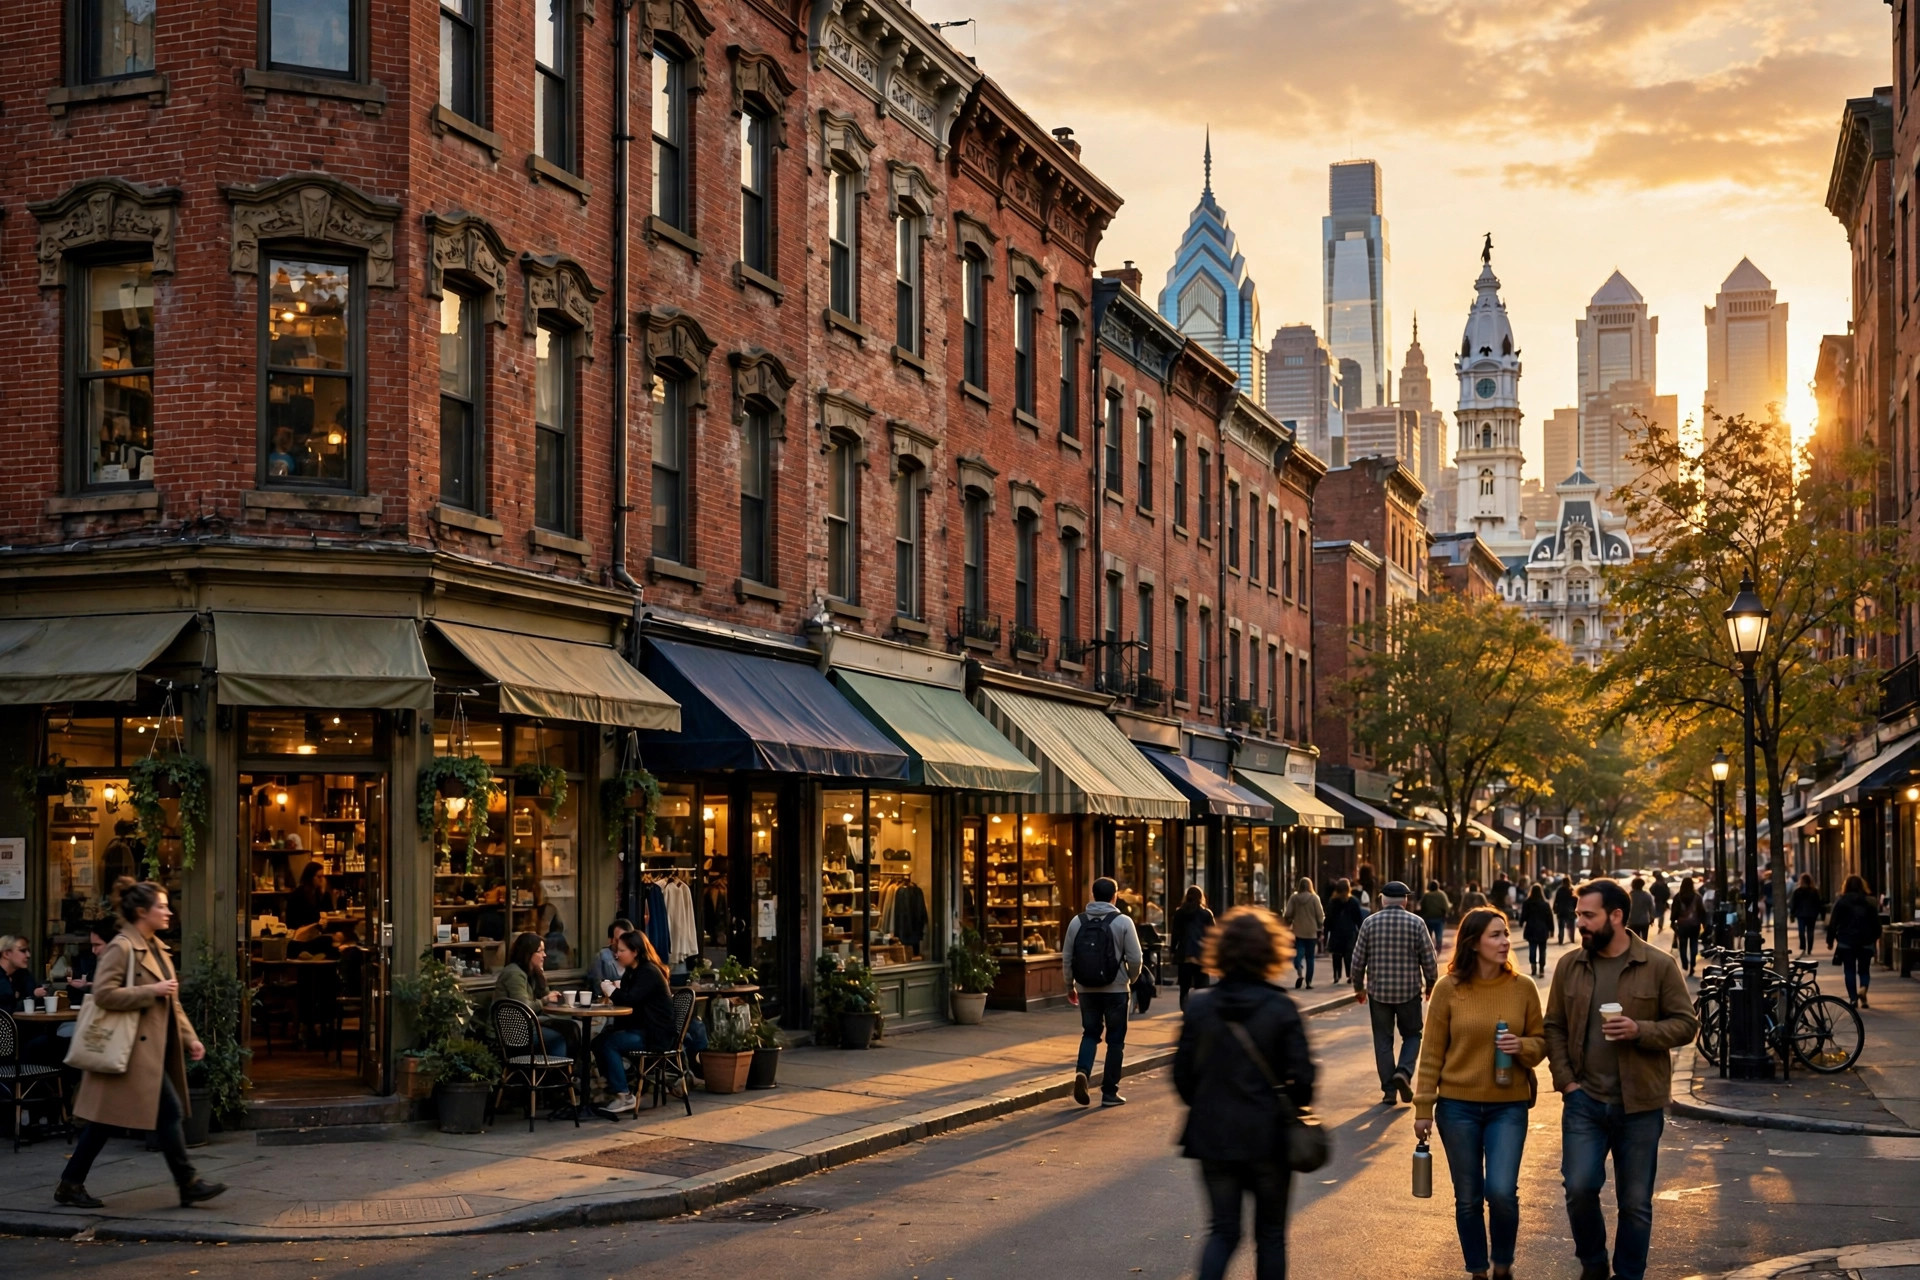
Key Takeaways
- Philadelphia is Pennsylvania's largest city and the sixth-largest city in the United States (about 1.57 million residents in the Census Bureau's 2025 estimates, with a metro area of roughly 6.2 million).
- Alternative lenders decide in hours and fund in 24–72 hours for Philadelphia businesses; banks typically take 30–90 days for the same money.
- The funding engines here are distinct: eds and meds in University City, historic tourism in Old City, the Fishtown and Northern Liberties restaurant corridor, South Philadelphia retail and food businesses, and Northeast Philadelphia industrial and logistics firms.
- 2026 is the nation's 250th anniversary year, and Philadelphia — the birthplace of American independence — sits at the center of the celebration, which means a real tourism and hospitality surge for Center City and Old City businesses.
Philadelphia is easy to misread as one market. It is really a dozen neighborhood economies stitched together by SEPTA lines: the hospital and university corridor in West Philadelphia, the historic district around Independence Hall, the restaurant rows of Fishtown and East Passyunk, the wholesale food and manufacturing blocks of South Philadelphia, and the industrial parks of the Northeast. Each one borrows for a different reason, on a different timeline — and each one gets a different answer from a bank.
A restaurant on Frankford Avenue needs to staff up before a weekend rush, not after it. A contractor serving a hospital system needs to float payroll between progress payments. A retailer near Independence Hall needs inventory before the summer tourism season, not during it. Traditional banks move slowly for all three — and often decline the smallest files outright. Alternative lenders underwrite on bank deposits, not paperwork volume, and fund in days.
What's in this guide
Why Philadelphia Businesses Need Fast Capital
Philadelphia's economy runs on several engines, and each one creates a different cash crunch.
Eds and meds. The University City corridor — the University of Pennsylvania, Drexel, Children's Hospital of Philadelphia, and Penn Medicine — anchors one of the largest education and healthcare employment centers in the country. Around it sits an ecosystem of suppliers, staffing firms, medical offices, labs, and student-serving retail. That work is steady, but it pays on institutional timelines: net-30 or net-45 terms are normal, and a supplier that lands a hospital contract often has to hire and stock up weeks before the first payment lands.
Historic tourism — supercharged in 2026. Old City, Society Hill, and the Independence Hall area draw visitors year-round, and 2026 brings the nation's 250th anniversary celebrations to the city where independence was declared. Hotels, restaurants, bars, tour operators, and retailers near the historic district face a genuine surge year — and need staff, inventory, and supplies funded before the crowds arrive, not after they leave.
The restaurant corridors. Fishtown and Northern Liberties, East Passyunk in South Philadelphia, and Rittenhouse in Center City form one of the densest restaurant scenes on the East Coast. Restaurants here borrow for build-outs, kitchen equipment, liquor-license-adjacent costs, and pre-opening payroll — and for the seasonal staffing swings that come with patio season and the holiday rush.
South Philadelphia food and manufacturing. The wholesale food distribution district, the Navy Yard's manufacturing and logistics tenants, and the stadium complex in South Philadelphia support a working economy of distributors, fabricators, trucking firms, and food businesses. Their needs are classic working capital: inventory, fleet maintenance, and payroll gaps between delivery and payment.
Northeast Philadelphia industry. Industrial parks along the Roosevelt Boulevard corridor and near the airport host warehousing, light manufacturing, and contractors. These firms borrow for equipment, vehicles, and materials — and for the gap between winning a job and getting paid for it.
Best Funding Options in Philadelphia
The headline numbers above describe the revenue-based market in general, not any single offer: actual terms depend on your deposits, time in business, and industry. What matters for a Philadelphia file is matching the product to the timing of the need.
Revenue-based funding (merchant cash advance). The workhorse for speed. Approval is driven by recent bank deposits, not by a perfect credit file, and funding lands in days. It fits seasonal staffing, inventory before a surge, and short-term gaps — and it is expensive relative to a bank loan, so it should be sized to a need that pays for itself quickly.
Business term loans. A fixed monthly payment over a set term, better for a defined purchase — a kitchen build-out, a delivery van, a second location's first-year rent — where the cost is known and the payback period is measured in years, not weeks.
Business lines of credit. Revolving access you draw only when needed. The best fit for the eds-and-meds supplier waiting on institutional payments, or the retailer smoothing the gap between inventory purchase and tourist-season sales.
Equipment financing. The equipment secures the loan, so underwriting is often easier than for unsecured working capital. A Fishtown restaurant's ovens, a Northeast Philly fabricator's press, or a distributor's refrigerated truck all fit here.
SBA loans. The cheapest money, and the slowest: 30–90 days is normal, and the paperwork bar is real. SBA fits the big, planned purchase — buying a building, a major expansion — not the payroll gap this Friday.
Which Product Fits Which Need
| Your need | Best first product | Why |
|---|---|---|
| Staff up before the 250th-anniversary tourism surge | Revenue-based funding | Funds in days, sized to the season |
| Float payroll while a hospital or university pays net-45 | Line of credit | Draw only what the gap requires, repay when the invoice clears |
| Kitchen build-out or restaurant equipment | Equipment financing or term loan | The asset secures it; payments match its useful life |
| Buy a second location or a building | SBA loan | Lowest cost for a long-lived asset — start early |
| Inventory before the holiday or summer season | Revenue-based funding or line of credit | Speed matters more than the last point of cost |
| Fleet repair or a delivery vehicle | Equipment financing | Vehicle as collateral, fast underwriting |
What Funders Actually Weigh on a Philadelphia File
Revenue-based funders start with your bank statements, not your business plan. Three things move the offer most:
Deposit consistency. Funders look for steady monthly deposits over the last 3–6 months. A restaurant with a strong summer and a soft winter still qualifies — but the offer is sized to the average, not the peak, and a sharp recent drop will shrink it.
Existing obligations. A business already carrying daily-debit payments gets a smaller offer, or a decline, because the funder is underwriting what is left after current payments. Paying down an existing advance before applying is the single most effective way to raise the next offer.
Industry and seasonality. Funders know Philadelphia's seasonal patterns — tourism summers, holiday retail, restaurant patio season — and they price for them. A file that explains its seasonality up front (last year's monthly deposits, the upcoming bookings) reads as lower risk than one that leaves the funder to guess.
Credit score matters less than most owners expect on revenue-based files: scores in the 500s routinely get funded, with the score affecting cost more than the yes-or-no. Bank and SBA files are stricter — typically 650-plus — and they also weigh time in business, collateral, and tax returns more heavily.
The Documents: Short List, No Surprises
For a revenue-based application, the standard ask is short:
- Last 3–6 months of business bank statements
- A completed application (owner, business, and revenue details)
- Government-issued ID and a voided check are sometimes requested for verification on specific products before funding — but neither is a universal upfront requirement to see your offers
Bank and SBA applications add tax returns, profit-and-loss statements, and often a business plan. If a lender asks for far more than this list for a small revenue-based advance, that is a sign to compare offers elsewhere.
Mistakes That Cost Philadelphia Businesses Real Money
Borrowing for a slow season with a fast product. Daily-debit funding is built for needs that generate cash quickly — a tourism surge, a big order, a seasonal inventory buy. Using it to cover a structural loss just stacks payments on top of a shortfall.
Signing on total repayment you never saw. Always get the total repayment dollars in writing before you sign — not just the factor rate or the monthly estimate. Two offers with the same advance amount can differ by thousands in total repayment.
Applying everywhere at once. Multiple applications in the same week can signal distress to funders. Apply through one broker who shops multiple funders, and compare the actual offers side by side.
Ignoring the lease. For a restaurant or retailer, the lease is the business: a short remaining term or a landlord who will not approve an assignment can kill an expansion plan. Sort the lease before you borrow for the build-out.
Frequently Asked Questions
How fast can a Philadelphia business get funded? Revenue-based products decide in hours and fund in 24–72 hours once statements are in. Equipment financing takes days to a couple of weeks. SBA products take a month or more.
Do I need a voided check or photo ID to apply? No — not to see offers. Bank statements and an application are the standard ask. A voided check or photo ID is sometimes requested for verification on specific products before funding, but neither is a universal upfront requirement.
What credit score do I need? Revenue-based funders weight bank deposits far more heavily than credit score, and scores in the 500s routinely get funded. SBA and bank products are stricter, typically 650-plus.
Does the 2026 anniversary celebration really change funding demand? Yes, for tourism-adjacent businesses. The 250th anniversary puts Philadelphia at the center of national attention in 2026, and hotels, restaurants, retailers, and tour operators near the historic district are staffing and stocking for a surge year — which is exactly the kind of short, predictable spike that fast funding is built for.
Can a new Philadelphia business get funded? A pre-revenue startup leans on SBA loans or a term loan underwritten on the owner's credentials and business plan, not on bank statements that do not exist yet. Revenue-based products need 3–6 months of deposits, so they come after opening, not before.
Philadelphia businesses: get your numbers in 24 hours
Tell us about your business and send your last 3 months of statements — we will compare multiple funders and put total repayment dollars in writing. No obligation, no upfront fees, no voided check required to see your offers.
Start your application or call (352) 809-3201
Ready to Get Funded?
Apply now and get a funding decision within hours. No hard credit pull for pre-approval — see your options risk-free.