Fast Business Funding in Wilmington, Delaware: Riverfront, Retail & Main Street Capital (2026)
Wilmington is Delaware's largest city and its business engine — Riverfront restaurants, Market Street retail, contractors, and service companies all need capital on local timelines. What fast funding looks like in Wilmington, which product fits which need, and how to compare offers.
Need funding fast? Apply in about 2 minutes — get a decision within hours, with no hard credit pull for pre-approval.
Apply Now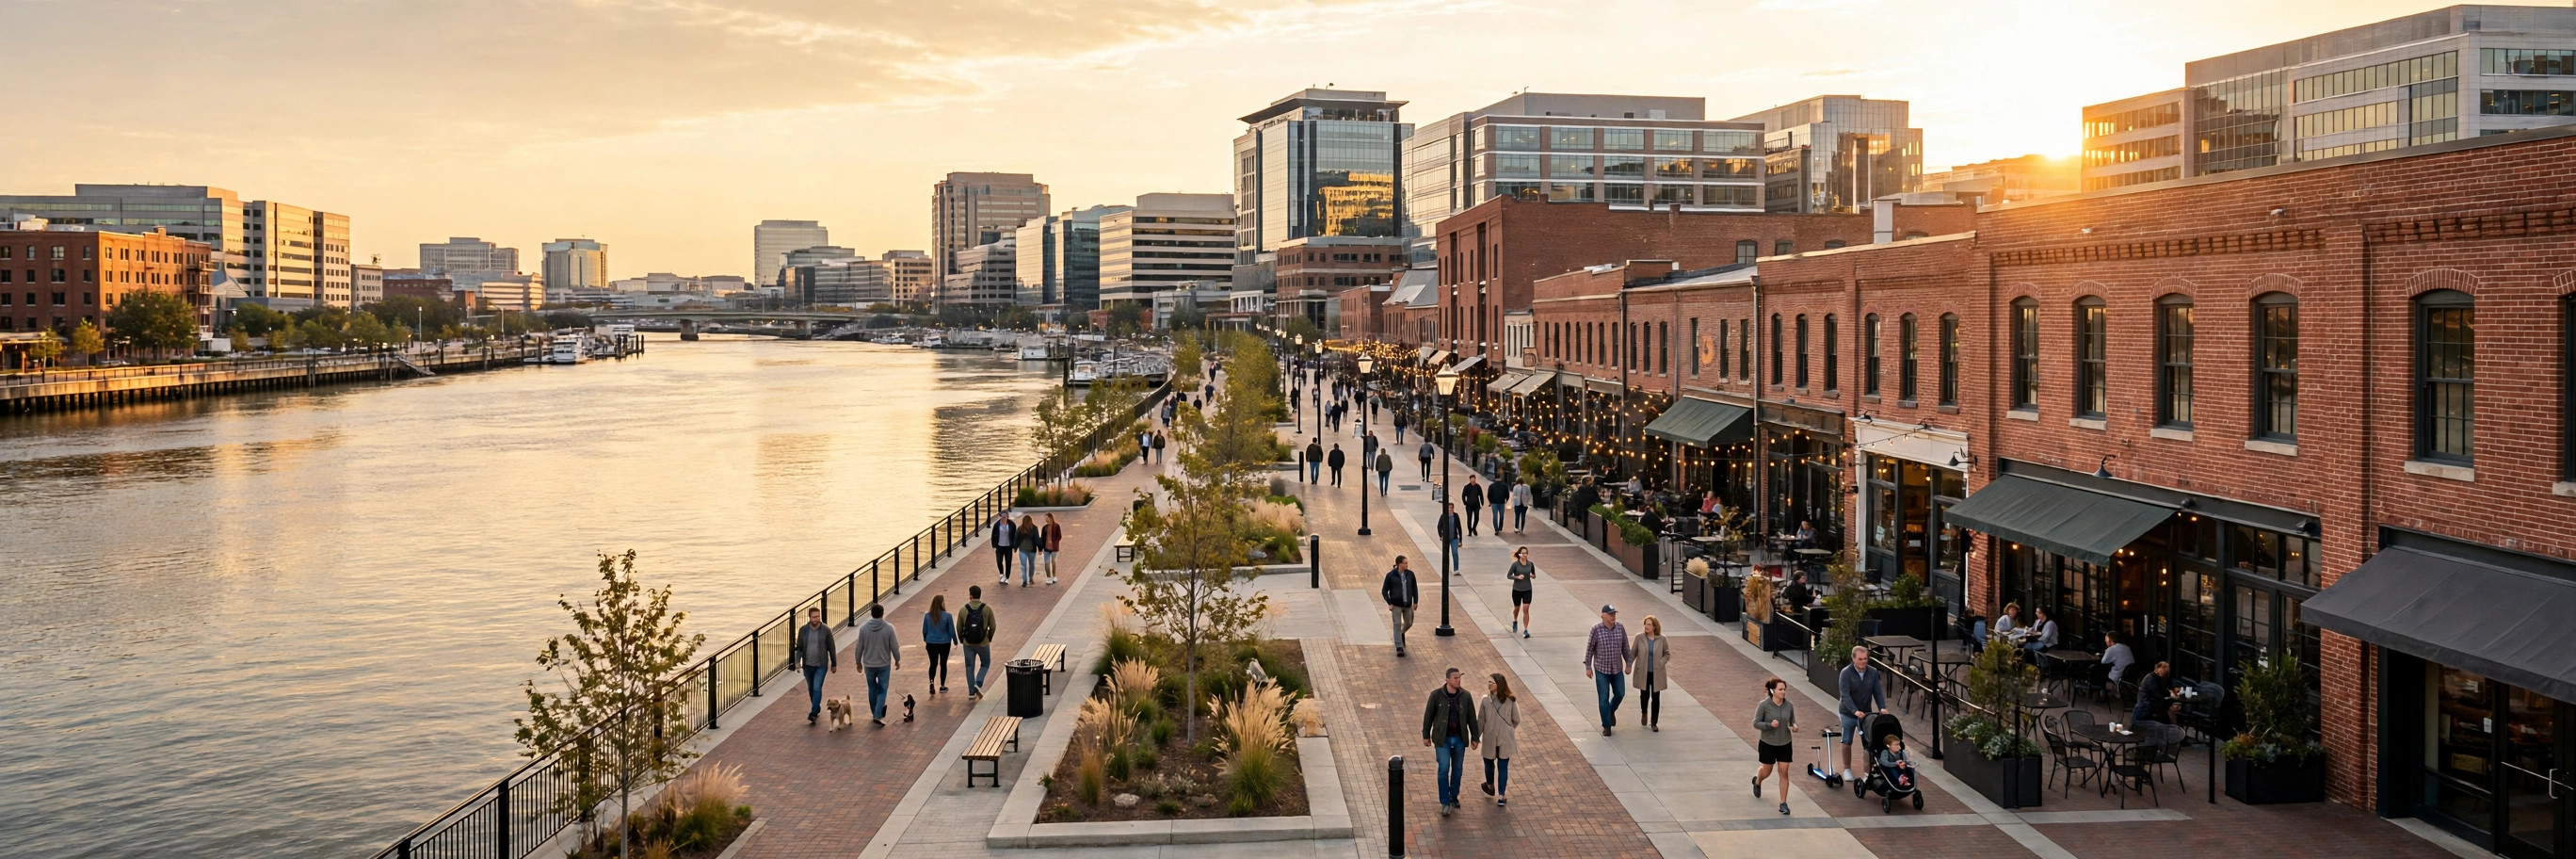
Key Takeaways
- Wilmington is Delaware's largest city (about 73,000 residents) and its corporate and financial hub, 30 minutes south of Philadelphia on the I-95 corridor.
- Alternative lenders decide in hours and fund in 24–72 hours for Wilmington businesses; banks typically take 30–90 days for the same money.
- The big three uses of funding are build-outs, equipment, and payroll float — Riverfront restaurants, Market Street retail, and contractors lead demand.
- Delaware has no sales tax, which draws regional shoppers and diners — and makes Wilmington retail and restaurant revenue less seasonal than in neighboring states.
Wilmington is easy to underestimate. Delaware's largest city holds roughly 73,000 people — small by East Coast standards — yet it anchors the state's corporate, financial, and legal economy, sits 30 minutes south of Philadelphia, and draws shoppers from three states with no sales tax. The Riverfront district, rebuilt from a former shipyard into restaurants, apartments, and offices, is now one of the city's busiest small-business corridors.
That mix creates a specific funding market. A Riverfront restaurant needs a build-out before it can open. A Market Street retailer needs inventory before the holiday season. A contractor serving the Philadelphia metro needs a second crew and a second truck before the next bid. Traditional banks move slowly for all three — and often decline the smallest files outright. Alternative lenders underwrite on bank deposits, not paperwork volume, and fund in days.
What's in this guide
Why Wilmington Businesses Need Fast Capital
Wilmington's economy runs on three engines, and each one creates a different cash crunch.
The Riverfront. Restaurants, bars, and entertainment venues cluster along the Christina River, where foot traffic follows events, games, and the summer season. A restaurant build-out — kitchen, bar, dining room, permits — has to be funded before the doors open, and the first months of rent and payroll arrive before the customer base does.
Market Street and downtown retail. Downtown Wilmington's retail and professional-service corridor serves 40,000-plus downtown workers plus regional shoppers drawn by tax-free shopping. Inventory, fixtures, and seasonal hiring all need cash ahead of revenue, especially before the holiday shopping season.
Contractors and trades. Wilmington contractors bid work across New Castle County and into Pennsylvania and Maryland. Winning a bid often means hiring a crew, buying materials, and floating payroll for weeks before the first progress payment lands. The companies that can staff up immediately win the work; the ones waiting on a bank decision watch it go to competitors.
Healthcare, professional services, and logistics. Wilmington's hospitals, law firms, and I-95 corridor warehouses all feed a service economy of suppliers, staffing firms, and specialty vendors — businesses with payroll and receivables gaps that do not wait for a bank committee.
Best Funding Options in Wilmington
Merchant Cash Advance (MCA)
Wilmington restaurants, retailers, and service businesses that take card payments are strong MCA candidates. The advance is based on monthly card volume and revenue, and repayment flexes with sales — useful for businesses whose revenue moves with events and seasons.
MCA highlights:
- Amounts: $10,000–$500,000+
- Approval based on: monthly card sales or revenue
- Time to funding: 24–72 hours
- Credit score: 500+ often acceptable
- Repayment: automatic, daily or weekly deductions from account
Short-Term Working Capital Loan
A lump-sum loan repaid over 3–18 months. The right fit for one-time needs: a build-out, a hiring push, a truck, or taking on a contract that pays on net-30 terms.
Working capital loan highlights:
- Amounts: $5,000–$500,000
- Time to funding: 24–72 hours for revenue-based products
- Credit score: 500+ often acceptable with steady deposits
- Repayment: fixed daily, weekly, or monthly schedule
Business Line of Credit
Draw, repay, and redraw as seasons turn. Wilmington's seasonal businesses — Riverfront restaurants, holiday retail, event-driven services — fit lines of credit better than fixed advances, because the gap repeats every year and the line is there every time.
Equipment Financing
For contractors, restaurants, and retailers buying named assets — a work truck, a commercial kitchen line, point-of-sale and fixtures. The asset secures the loan, which usually means better terms than an unsecured advance.
SBA Loans
For larger, longer-term needs — a second location, a major build-out, a business purchase. SBA loans cost less but take 30–90 days to close, so they fit planned expansions, not emergencies.
Which Product Fits Which Wilmington Need
| Need | Best fit | Why |
|---|---|---|
| Riverfront restaurant build-out | Term loan or SBA loan | Larger amounts, longer payoff, lower cost when time allows |
| Holiday inventory for Market Street retail | Working capital loan or line of credit | Cash ahead of the season, repaid after it |
| Contractor crew and materials for a new bid | Merchant cash advance or working capital loan | Decision in hours, funding in 24–72 hours |
| Work truck or kitchen equipment | Equipment financing | Asset secures the loan; payments matched to equipment life |
| Payroll before the first client check | Working capital loan / MCA | Fast money for a gap measured in weeks |
| Recurring seasonal gaps | Business line of credit | Draw, repay, redraw as seasons turn |
What Funders Actually Weigh on a Wilmington File
Bank deposits, not the business plan. Funders underwrite on the last 3 months of bank statements: average monthly deposits, deposit frequency, and whether balances stay positive. A Wilmington business with steady deposits is a fundable file even with a modest credit score.
Location revenue, honestly stated. Riverfront and downtown businesses should expect questions about foot traffic and seasonality. A restaurant that surges in summer and dips in winter is not a weak file — it is a seasonal file. Funders would rather see the pattern named and planned for than discover it in the statements.
The lease. Time left on the lease matters, especially for build-out funding. A funder financing a six-figure fit-out wants to know the business will still be in the space long enough to earn it back.
Concentration. One client or one event series at 60% of revenue is a risk flag. Funders prefer revenue spread across several sources, so losing one does not sink the company.
Delaware advantage, priced in. No sales tax and a lower cost of doing business than Philadelphia or New York are real Wilmington advantages — but funders underwrite deposits, not tax policy. The advantage shows up in margins, and margins show up in statements.
The Documents: Short List, No Surprises
- Last 3 months of business bank statements — the one document every funder requires
- Vendor quotes for any equipment being financed
- Lease copy, for build-out or expansion funding
- Signed contracts, to show recurring revenue on contractor files
- Photo ID and a voided check available if a specific product's verification asks — neither is required upfront to see offers
Mistakes That Cost Wilmington Businesses Real Money
Funding a build-out with a daily-debit advance. A build-out lasts years; a daily-debit advance is repaid in months. Match the payoff to the purchase, or the payments eat the margin the build-out was supposed to create.
Taking a contract you cannot staff. The fastest way to lose a commercial account is to miss the first delivery. Do not fund the materials for a contract before you have funded the crew to service it.
Signing the lease before the funding is lined up. A signed lease with no build-out money is a countdown clock. Get the funding answer before the deposit is non-refundable.
Carrying net-30 clients on an advance. If your biggest client pays in 45 days and you are funding payroll on daily debits, the math works against you every week. Price the terms in, factor the invoices, or negotiate faster payment — do not carry slow payers on fast money.
Taking the first offer. Getting two or three offers and comparing total repayment dollars typically saves thousands on the same advance. The first offer is rarely the best one.
Wilmington Business Funding FAQ
Can a new Wilmington business get funded? Most alternative funders want at least 3–6 months of bank history. Under 3 months, options narrow sharply — a strong personal credit profile and signed contracts help, but expect smaller amounts.
Does bad credit kill the deal? No. MCA and revenue-based underwriting weights bank deposits far more heavily than credit score. Scores in the 500s routinely get funded; the score affects the cost of the offer, not usually the yes-or-no.
How fast is funding, really? If your application and statements are in before mid-morning and underwriting clears the same day, funding can land that evening or the next morning. Afternoon applications usually fund the next business day.
Is Wilmington different from Newark or Middletown? Yes. Newark and Middletown are smaller, more residential markets. Wilmington is Delaware's commercial center — Riverfront dining, downtown retail, and contractors bidding across three states — so the funding needs skew larger and more build-out heavy.
Do I need a voided check or photo ID to apply? No — not to see offers. Bank statements and an application are the standard ask. A voided check or photo ID is sometimes requested for verification on specific products before funding, but neither is a universal upfront requirement.
Wilmington businesses: get your numbers in 24 hours
Tell us about your business and send your last 3 months of statements — we'll compare multiple funders and put total repayment dollars in writing. No obligation, no upfront fees, no voided check required to see your offers.
Start your application or call (352) 809-3201
Ready to Get Funded?
Apply now and get a funding decision within hours. No hard credit pull for pre-approval — see your options risk-free.